Mixed-use properties can create unique opportunities for real estate investors by combining residential units with commercial space in a single property. However, financing these properties can sometimes be more complicated than financing a traditional residential investment property.
Tag Lending Group offers 2–8 Unit Mixed-Use Financing designed for investors purchasing or refinancing properties that combine residential units with eligible commercial uses such as retail, restaurant, and office space.
What Is a Mixed-Use Property?
A mixed-use property combines more than one type of real estate use within the same building or property. A common example is a building with residential apartments on the upper floors and retail, restaurant, or office space on the ground floor.
These properties can provide investors with multiple potential sources of rental income while allowing them to diversify the use of a single asset.
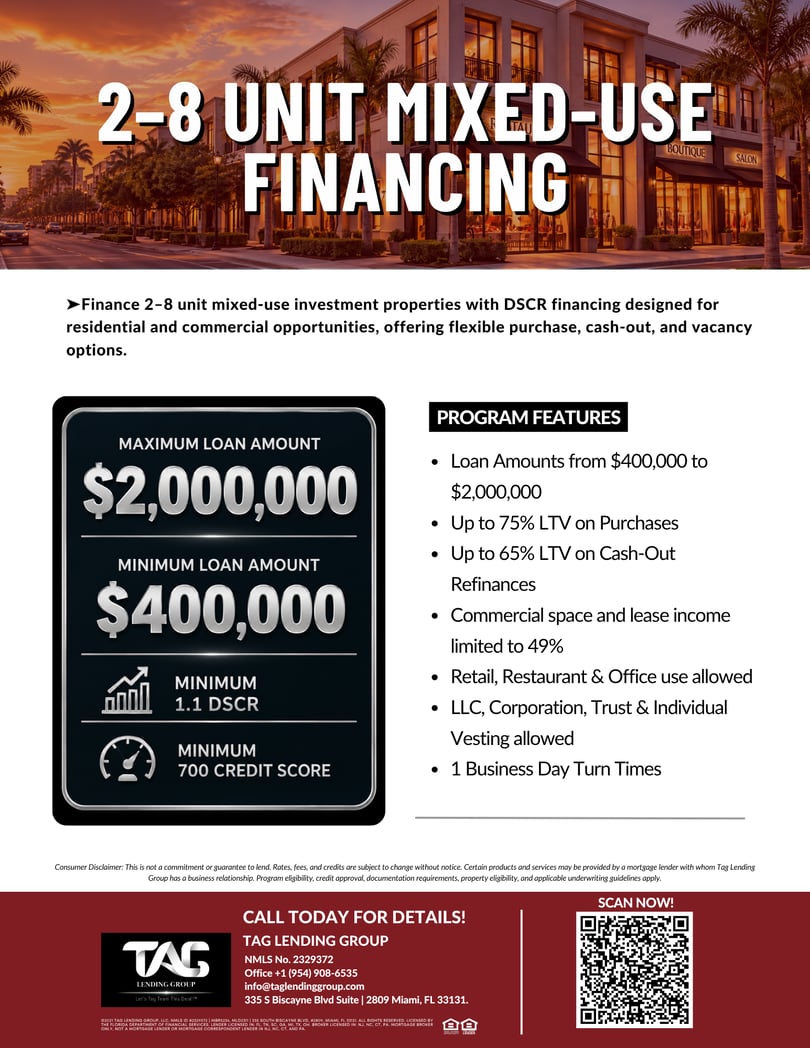
2–8 Unit Mixed-Use Program Highlights
Eligible investors may have access to financing with:
- Loan amounts from $400,000 to $2,000,000
- Minimum 1.10 DSCR
- Minimum 700 credit score
- Up to 75% LTV on purchases
- Up to 65% LTV on cash-out refinances
- Commercial space and lease income limited to 49%
- Retail, restaurant, and office use allowed
- LLC, corporation, trust, and individual vesting allowed
- 1-business-day turn times
Program eligibility and final terms are subject to underwriting guidelines and approval.
Why DSCR Financing Can Work for Mixed-Use Investors
Debt Service Coverage Ratio, or DSCR, financing focuses on the property's ability to generate sufficient income relative to its debt obligation.
For real estate investors, this can provide another way to evaluate an investment property without relying exclusively on traditional owner-occupied mortgage qualification methods.
For qualifying mixed-use properties, this approach can be particularly useful when the property generates income from both residential and commercial tenants.
Purchase Mixed-Use Investment Properties
Investors looking to acquire a qualifying 2–8 unit property may be eligible for financing up to 75% LTV.
This may create opportunities for investors considering properties such as:
- Apartment units above retail storefronts
- Residential units combined with office space
- Residential buildings with restaurants at street level
- Small mixed-use multifamily properties
- Neighborhood commercial buildings with residential units
Cash-Out Refinance Opportunities
Existing mixed-use property owners may also be able to access equity through a cash-out refinance up to 65% LTV, subject to program requirements.
Depending on the investor's objectives, accessing equity may provide capital for additional real estate investments, property improvements, or other investment-related purposes.
Commercial Space Flexibility
Under this program, commercial square footage and commercial lease income can represent up to 49% of the property.
Eligible commercial uses may include:
Retail | Restaurant | Office
This provides investors with additional flexibility when evaluating properties that do not fit neatly into a traditional residential-only lending category.
Who Is This Program For?
This financing option is designed for real estate investors purchasing or refinancing 2–8 unit mixed-use properties that combine residential units with qualifying commercial space.
It may be especially useful for investors looking to acquire properties with multiple income streams or expand into mixed-use real estate.
How DSCR Is Calculated on a Mixed-Use Property
DSCR compares the property's qualifying rental income to its monthly housing expense: principal, interest, taxes, insurance and any association dues (PITIA). On a mixed-use building, both the residential rents and the commercial lease income can count toward qualifying income, within the program's 49% commercial limit.
Simple example: if a four-unit building with a ground-floor storefront produces qualifying monthly income equal to 1.25 times its monthly PITIA, the DSCR is 1.25. This program requires a minimum of 1.10. How income is treated (lease rent vs. market rent, vacancy factors) is set by underwriting and the appraisal.
Inputs underwriting will look at:
- Residential leases and the appraiser's market rent schedule
- Commercial lease terms, tenant type and remaining lease term
- Property taxes, insurance (including commercial liability) and any association dues
Documents Investors Should Have Ready
Mixed-use files move faster when the package is complete up front. Brokers and investors can typically expect underwriting to request:
- Executed residential and commercial leases and a current rent roll
- Entity documents when vesting in an LLC, corporation or trust (articles, operating agreement, EIN, good standing)
- Purchase contract, or for a refinance, the current mortgage statement
- Proof of funds for down payment, closing costs and reserves
- Insurance quotes covering both the residential units and the commercial space
- Access details for the appraisal, including commercial tenant contacts
Final documentation requirements are set by underwriting and can vary by property and investor profile.
Mixed-Use Opportunities in Florida
South Florida's walkable corridors in Miami-Dade, Broward and Palm Beach are full of small buildings with shops or offices on the ground floor and apartments above. Many of these properties fall outside residential-only guidelines, yet they are often too small for a traditional commercial bank loan. A 2–8 unit mixed-use DSCR program is built for that gap.
Tag Lending Group is headquartered in Miami and licensed as a mortgage lender in Florida, Georgia, Michigan, New Mexico, Ohio, South Carolina, Tennessee and Texas. Program availability varies by state and property type.
Common Issues That Slow Down Mixed-Use Deals
- Commercial use above 49% of square footage or income, which may push the deal to a commercial loan
- Vacant commercial space with no lease in place
- Commercial uses outside retail, restaurant and office
- Zoning or legal nonconforming use questions raised by the appraisal
- Short remaining lease terms on the commercial tenant
- Missing entity documents when closing in an LLC
Flagging these early lets the broker or MLO structure the file correctly before submission.
How Brokers and MLOs Submit a Mixed-Use Deal to TAG
Tag Lending Group works with mortgage brokers, MLOs and Realtor partners through our wholesale and non-delegated correspondent channels. To scenario a 2–8 unit mixed-use deal, send the property type, unit mix, commercial square footage, current or projected rents, purchase price or estimated value, and planned vesting. Our team will review program fit and next steps. Licensed partners can also work deals with us as a Co-Org Loan.
Explore our full DSCR loan program, or see why loan officers partner with TAG.
2–8 Unit Mixed-Use Financing FAQ
What is a 2–8 unit mixed-use property?
A building with two to eight residential units plus commercial space such as retail, restaurant or office. Under this program, commercial use can represent up to 49% of the property's square footage and lease income.
Can commercial lease income count toward DSCR?
Yes. Qualifying commercial lease income can be included alongside residential rents, within the 49% limit and subject to underwriting.
Can I close a mixed-use DSCR loan in an LLC?
Yes. LLC, corporation, trust and individual vesting are allowed, subject to review of the entity documents.
What are the minimum DSCR and credit score?
The program requires a minimum 1.10 DSCR and a minimum 700 credit score. Final eligibility and terms are subject to underwriting.
Is a cash-out refinance available on mixed-use properties?
Yes. Cash-out refinances are available up to 65% LTV, and purchases up to 75% LTV, subject to program requirements.
How do brokers submit a mixed-use scenario to TAG?
Send the unit mix, commercial square footage, rents, value or price and vesting to the TAG team and we will review program fit. Brokers and MLOs can partner with TAG through our wholesale and non-delegated correspondent channels.
Program guidelines are subject to change. All loans are subject to underwriting and approval. Tag Lending Group LLC, NMLS #2329372. Equal Housing Opportunity.
Download Our Cheat Sheet!
Unlocking Real Estate Success:
Tag Lending Group's Client Funnel Retention Program
In this dynamic video, we break down the essential components of our intake form and showcase how it empowers you to understand your return on investment, lead sources, and client demographics. Discover how we harness this data to fine-tune your marketing strategy and drive impressive results.🏠🔑