Affordable government-backed financing with flexible down payment options
A borrower-friendly mortgage solution designed to help eligible homebuyers purchase a primary residence with flexible credit guidelines, low down payment options, and accessible qualification features.
The FHA Home Loan Program is designed for eligible borrowers who want an accessible path to homeownership. With flexible credit guidelines, low down payment options, and borrower-friendly qualification features, this program can be a strong fit for buyers purchasing a primary residence and clients who need more flexibility than some conventional loan options may allow.
Minimum down payment may be as low as 3.5% for qualified borrowers.
Credit score options may start at 580, with additional options possible for lower scores with a larger down payment.
Maximum debt-to-income ratio may allow up to 50% depending on borrower qualification.
The home must be used as the borrower’s primary residence.
The property must meet FHA safety, security, and soundness standards.
Closing cost funds are typically needed and may be covered by eligible seller, builder, or lender contributions.
Helps make homeownership more accessible with low down payment options.
Can support borrowers who need more flexible credit guidelines than some conventional programs.
Allows higher debt-to-income flexibility for qualified borrowers.
May allow seller, builder, or lender contributions to help with closing costs.
Gives realtors another helpful solution for buyers who need an accessible primary residence financing option.
Creates a clear path to discuss credit, down payment, funds to close, and property eligibility with a loan officer.
Homebuyers purchasing a primary residence.
Borrowers who may benefit from a low down payment mortgage option.
Clients with credit profiles that may need more flexibility than standard conventional financing.
Buyers who need guidance on down payment, closing costs, and qualification readiness.
Borrowers who have stable employment history and are ready to explore primary home financing.
Realtors working with buyers who need an accessible and flexible home loan solution.
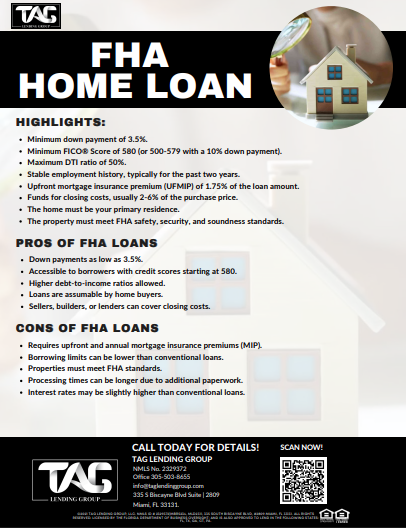
Preview the loan program sheet and download the full FHA Home Loan Program details instantly.
Access the co-branded version to share this FHA Home Loan Program with your clients and referral partners.
Connect with a loan officer to review your borrower scenario and get clear guidance on the best next step.
Connect To A Loan OfficerAn FHA loan is a mortgage insured by the Federal Housing Administration. It allows a smaller down payment and more flexible credit guidelines than many conventional loans, and it requires mortgage insurance.
Often, yes. Florida down payment assistance programs, including Florida Hometown Heroes when it is funded, can pair with eligible first mortgages. Funding, income limits and eligibility vary, so your loan officer will confirm what is available.
Yes, if the project is FHA-approved or the unit qualifies for a single-unit approval. TAG Lending Group (NMLS #2329372) lends in FL, GA, MI, NM, OH, SC, TN and TX.
FHA loans may be available with a 580 credit score and 3.5% down. Manual underwriting can go as low as a 500 score with 10% down for qualifying scenarios. Final eligibility depends on the full borrower profile.
As little as 3.5% with a 580 credit score, and 10% for scores starting at 500.
FHA loans require mortgage insurance with an upfront premium and an annual premium. A loan officer can review how it applies to your scenario. Mortgage insurance premiums may be tax deductible beginning with tax year 2026 for eligible borrowers who itemize and whose adjusted gross income is below $109,000 (the deduction phases out starting at $100,000). Speak with your CPA or tax advisor. TAG Lending Group does not provide tax advice.
It may be. Mortgage insurance premiums may be tax deductible beginning with tax year 2026 for eligible borrowers who itemize deductions, on a primary residence or second home, with adjusted gross income below $109,000 (the deduction phases out starting at $100,000). Speak with your CPA or tax advisor about your situation. TAG Lending Group does not provide tax advice.
Yes, if you live in one of the units as your primary residence and the property meets FHA standards.
A simplified refinance of an existing FHA loan with reduced documentation, including credit-qualifying and non-credit-qualifying options. Eligibility varies by loan history and scenario.
Yes. FHA loan limits are set by county, and FHA High Balance may apply in higher-cost counties.
Gift funds are generally allowed for the down payment with proper documentation.
Borrowers without a traditional credit history may qualify using non-traditional credit references. Ask a TAG loan officer about your options.
An FHA loan is a government-insured mortgage for primary residences. Borrowers may qualify with 3.5% down at a 580 credit score, or from a 500 score with 10% down using manual underwriting. Mortgage insurance is required and may be tax deductible for eligible borrowers (speak with your CPA). TAG Lending Group lends in FL, GA, MI, NM, OH, SC, TN and TX. Last reviewed: November 2026.
3.5% Down
Minimum down payment at 580 FICO for qualified borrowers
500 FICO
Manual underwriting from 500 FICO with 10% down (90% LTV) for qualifying scenarios
Tax Deductible
Mortgage insurance may be tax deductible beginning in tax year 2026 for eligible borrowers who itemize with AGI below $109,000. Speak with your CPA.
County Limits
Loan limits are set by county; FHA High Balance may apply in higher-cost counties
1-4 Units
Owner-occupied primary residences, including 2-4 unit properties
Manual underwriting is available down to 500 FICO with 10% down for qualifying scenarios.
Non-traditional credit may be accepted for borrowers without a traditional credit history.
FHA Streamline refinance options may be available for existing FHA borrowers, including credit-qualifying and non-credit-qualifying.
Gift funds may be used for the down payment, subject to documentation.
2-4 unit properties are eligible when the borrower occupies one unit as a primary residence.
FHA loans require mortgage insurance, made up of an upfront premium and an annual premium. Mortgage insurance may be tax deductible for eligible borrowers. Speak with your CPA. TAG Lending Group does not provide tax advice.