Conventional High Balance Program
A conventional mortgage solution for qualified borrowers purchasing or refinancing higher-priced properties that exceed standard conforming loan limits in eligible high-cost areas.
Program Overview
The Conventional High Balance Program is designed for qualified borrowers who need conventional financing for higher-priced homes in eligible high-cost areas. This program can help borrowers access loan amounts above standard conforming limits while still using a familiar conventional mortgage structure.
Program Features
Designed for qualified borrowers seeking high balance conventional mortgage financing.
Can support loan amounts above standard conforming limits in eligible high-cost areas.
May be used for eligible home purchase and refinance scenarios.
A strong option for borrowers purchasing higher-priced primary residences, second homes, or eligible investment properties.
Provides a conventional financing path for borrowers who need more loan capacity than standard conforming limits allow.
Can be reviewed with a loan officer based on borrower profile, property location, occupancy type, and loan amount needs.
Why Choose This Program?
Helps borrowers finance higher-priced properties while staying within a conventional loan framework.
Can provide a practical option for buyers in high-cost markets where standard loan limits may not be enough.
Supports a familiar qualification process for borrowers with traditional income, credit, and documentation profiles.
Gives realtors another financing solution for clients shopping in higher-price ranges.
May help qualified borrowers avoid needing a jumbo loan when a high balance conventional option is available.
Creates a clear path to review purchase or refinance options for higher loan amount scenarios.
Who This Program Is Great For?
Borrowers purchasing higher-priced homes in eligible high-cost areas.
Homeowners refinancing properties with loan amounts above standard conforming limits.
Qualified borrowers who want a conventional structure for a larger loan amount.
Clients buying in higher-cost markets where standard conforming limits may not meet their needs.
Borrowers with stable income, solid credit, and standard documentation who need higher loan capacity.
Realtors working with qualified buyers in higher-priced neighborhoods or high-cost counties.
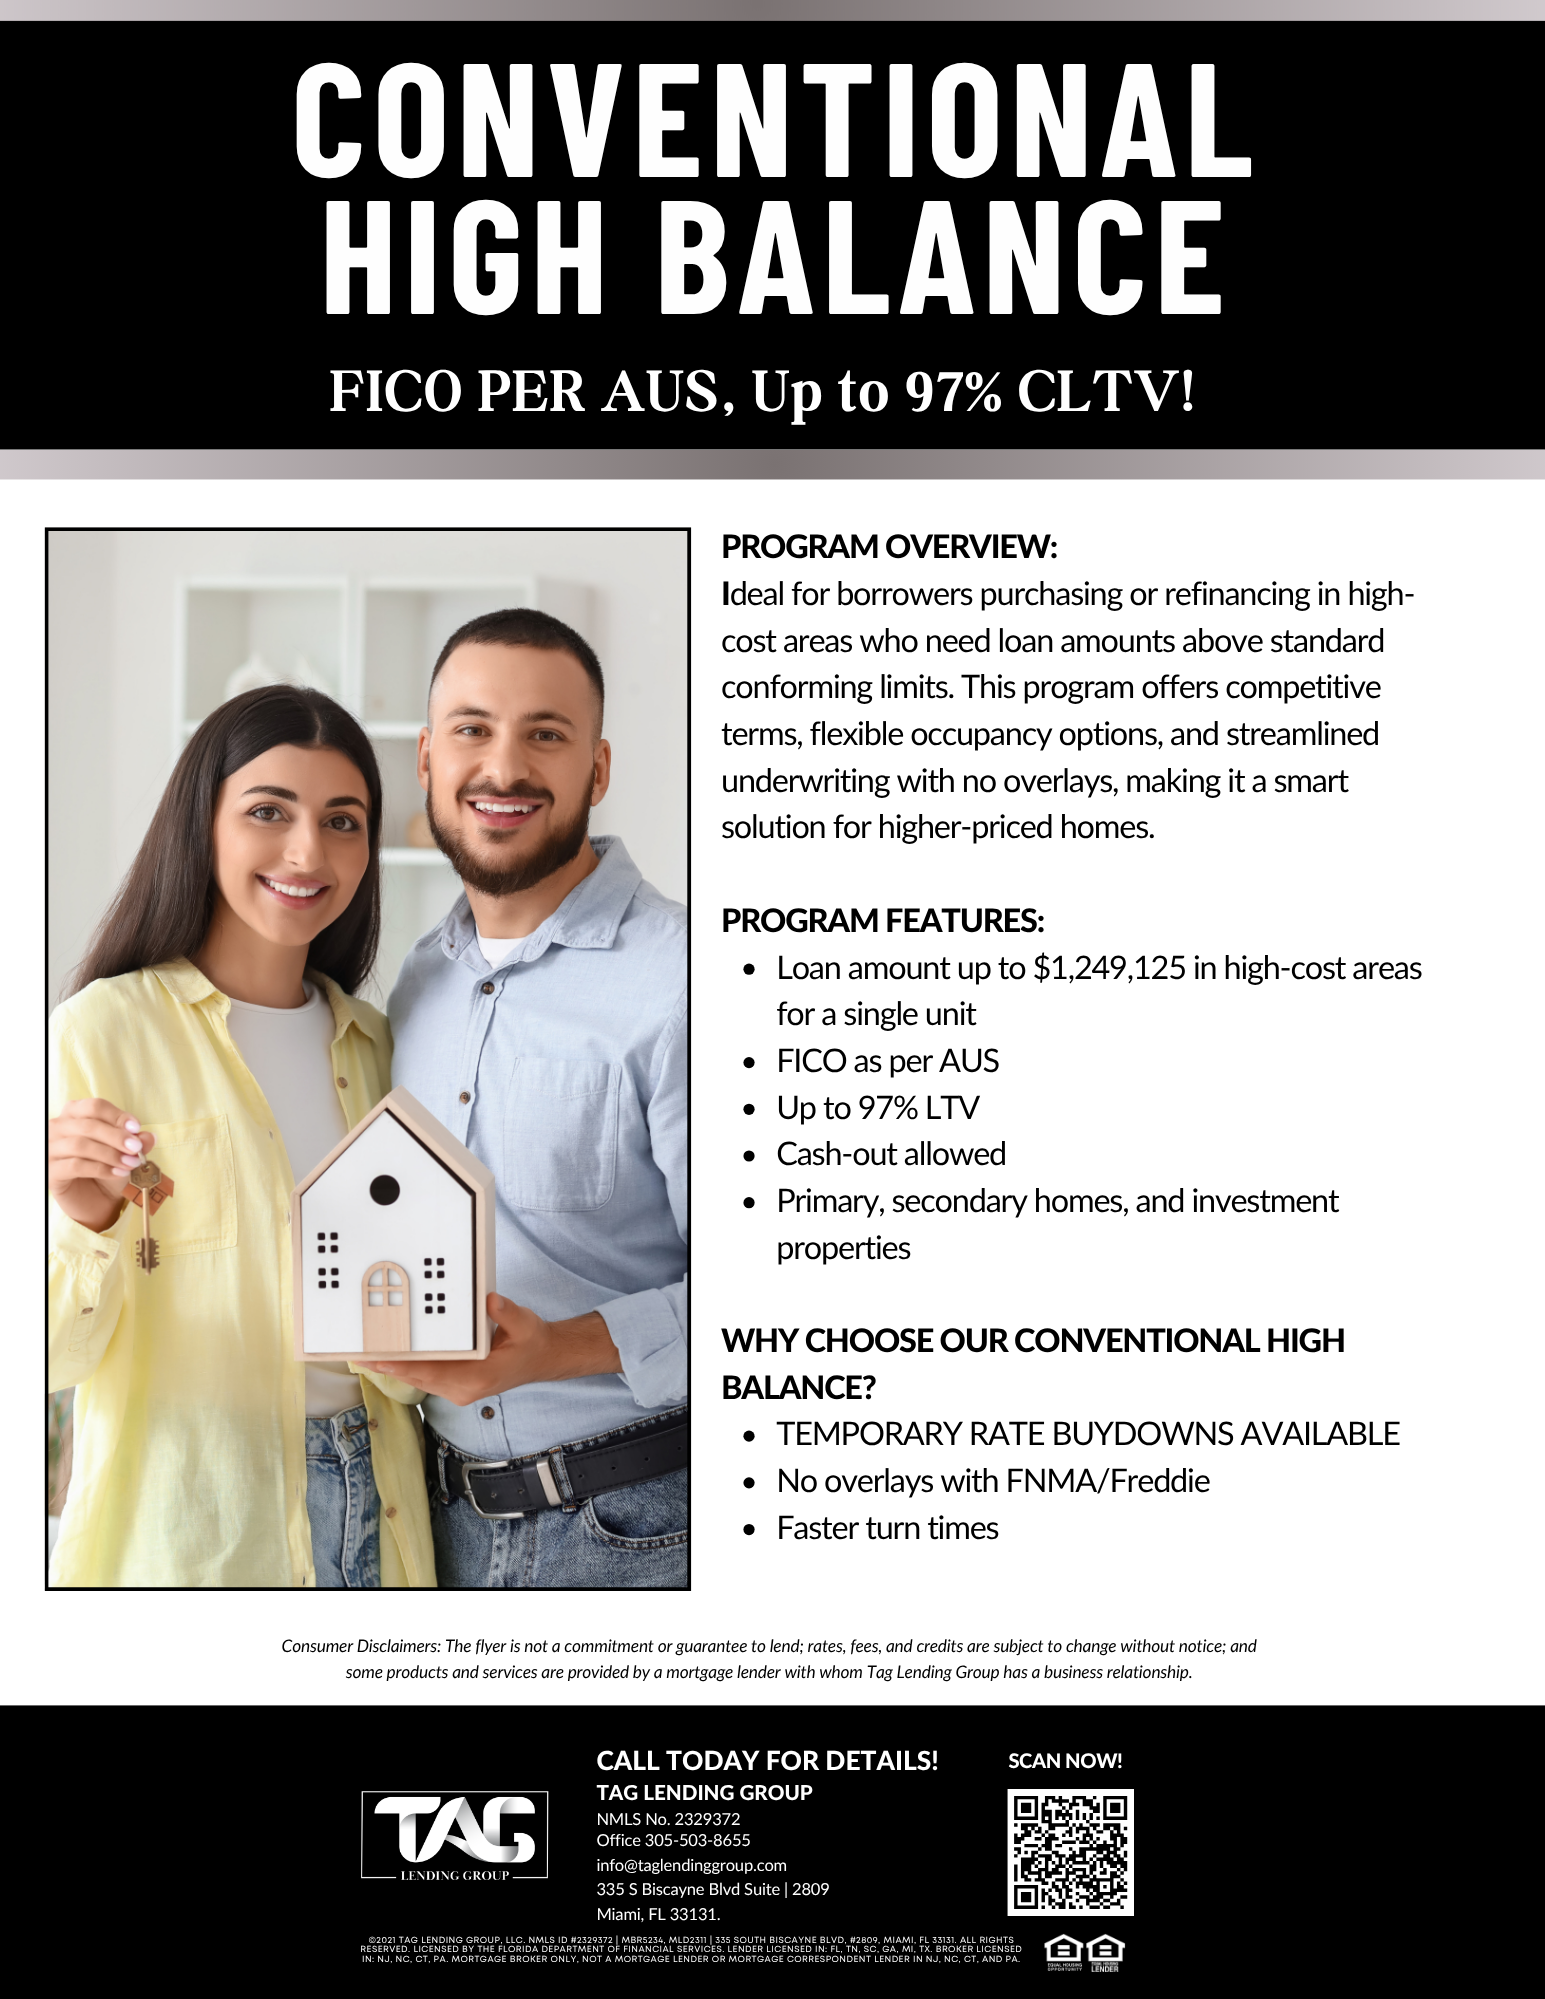
Download Loan Program
Preview the loan program sheet and download the full Conventional High Balance Program details instantly.
Co-Brand Loan Program
Access the co-branded version to share this Conventional High Balance Program with your clients and referral partners.
Need Help Structuring a Conventional High Balance Loan?
Connect with a loan officer to review your borrower scenario and get clear guidance on the best next step.
Connect To A Loan Officer