Streamlined financing for multiple investment properties under one loan structure
A streamlined financing solution designed for real estate investors who want to finance multiple rental properties under one portfolio or blanket loan structure.
Portfolio and Blanket Loans are designed for real estate investors who want to finance multiple investment properties through a more consolidated lending structure. Instead of managing separate financing for every property, qualified investors may be able to place multiple rental properties into one portfolio transaction, creating a more streamlined approach to financing and portfolio management.
Designed specifically for investment property portfolios.
Allows multiple eligible rental properties to be financed within a portfolio or blanket structure.
Available for qualified purchase, rate-and-term refinance, and cash-out refinance scenarios.
Can help investors consolidate multiple property loans into a more streamlined financing structure.
Supports entity vesting options for eligible real estate investors.
Designed to support investors as they expand and manage larger rental portfolios.
Simplifies financing by combining multiple investment properties into a portfolio strategy.
A strong option for investors who have outgrown traditional single-property financing.
Can reduce the administrative burden of managing numerous individual property loans.
Helps experienced investors structure larger acquisition or refinance opportunities.
Provides greater flexibility for investors managing several rental properties.
Creates another financing path for borrowers focused on building and scaling a real estate portfolio.
Real estate investors with multiple rental properties.
Investors purchasing several properties as part of one acquisition strategy.
Borrowers looking to refinance and consolidate an existing rental portfolio.
Experienced investors who want to simplify multiple property loans.
Investors seeking financing beyond traditional property-count limitations.
Clients who want guidance on structuring a portfolio or blanket loan transaction.
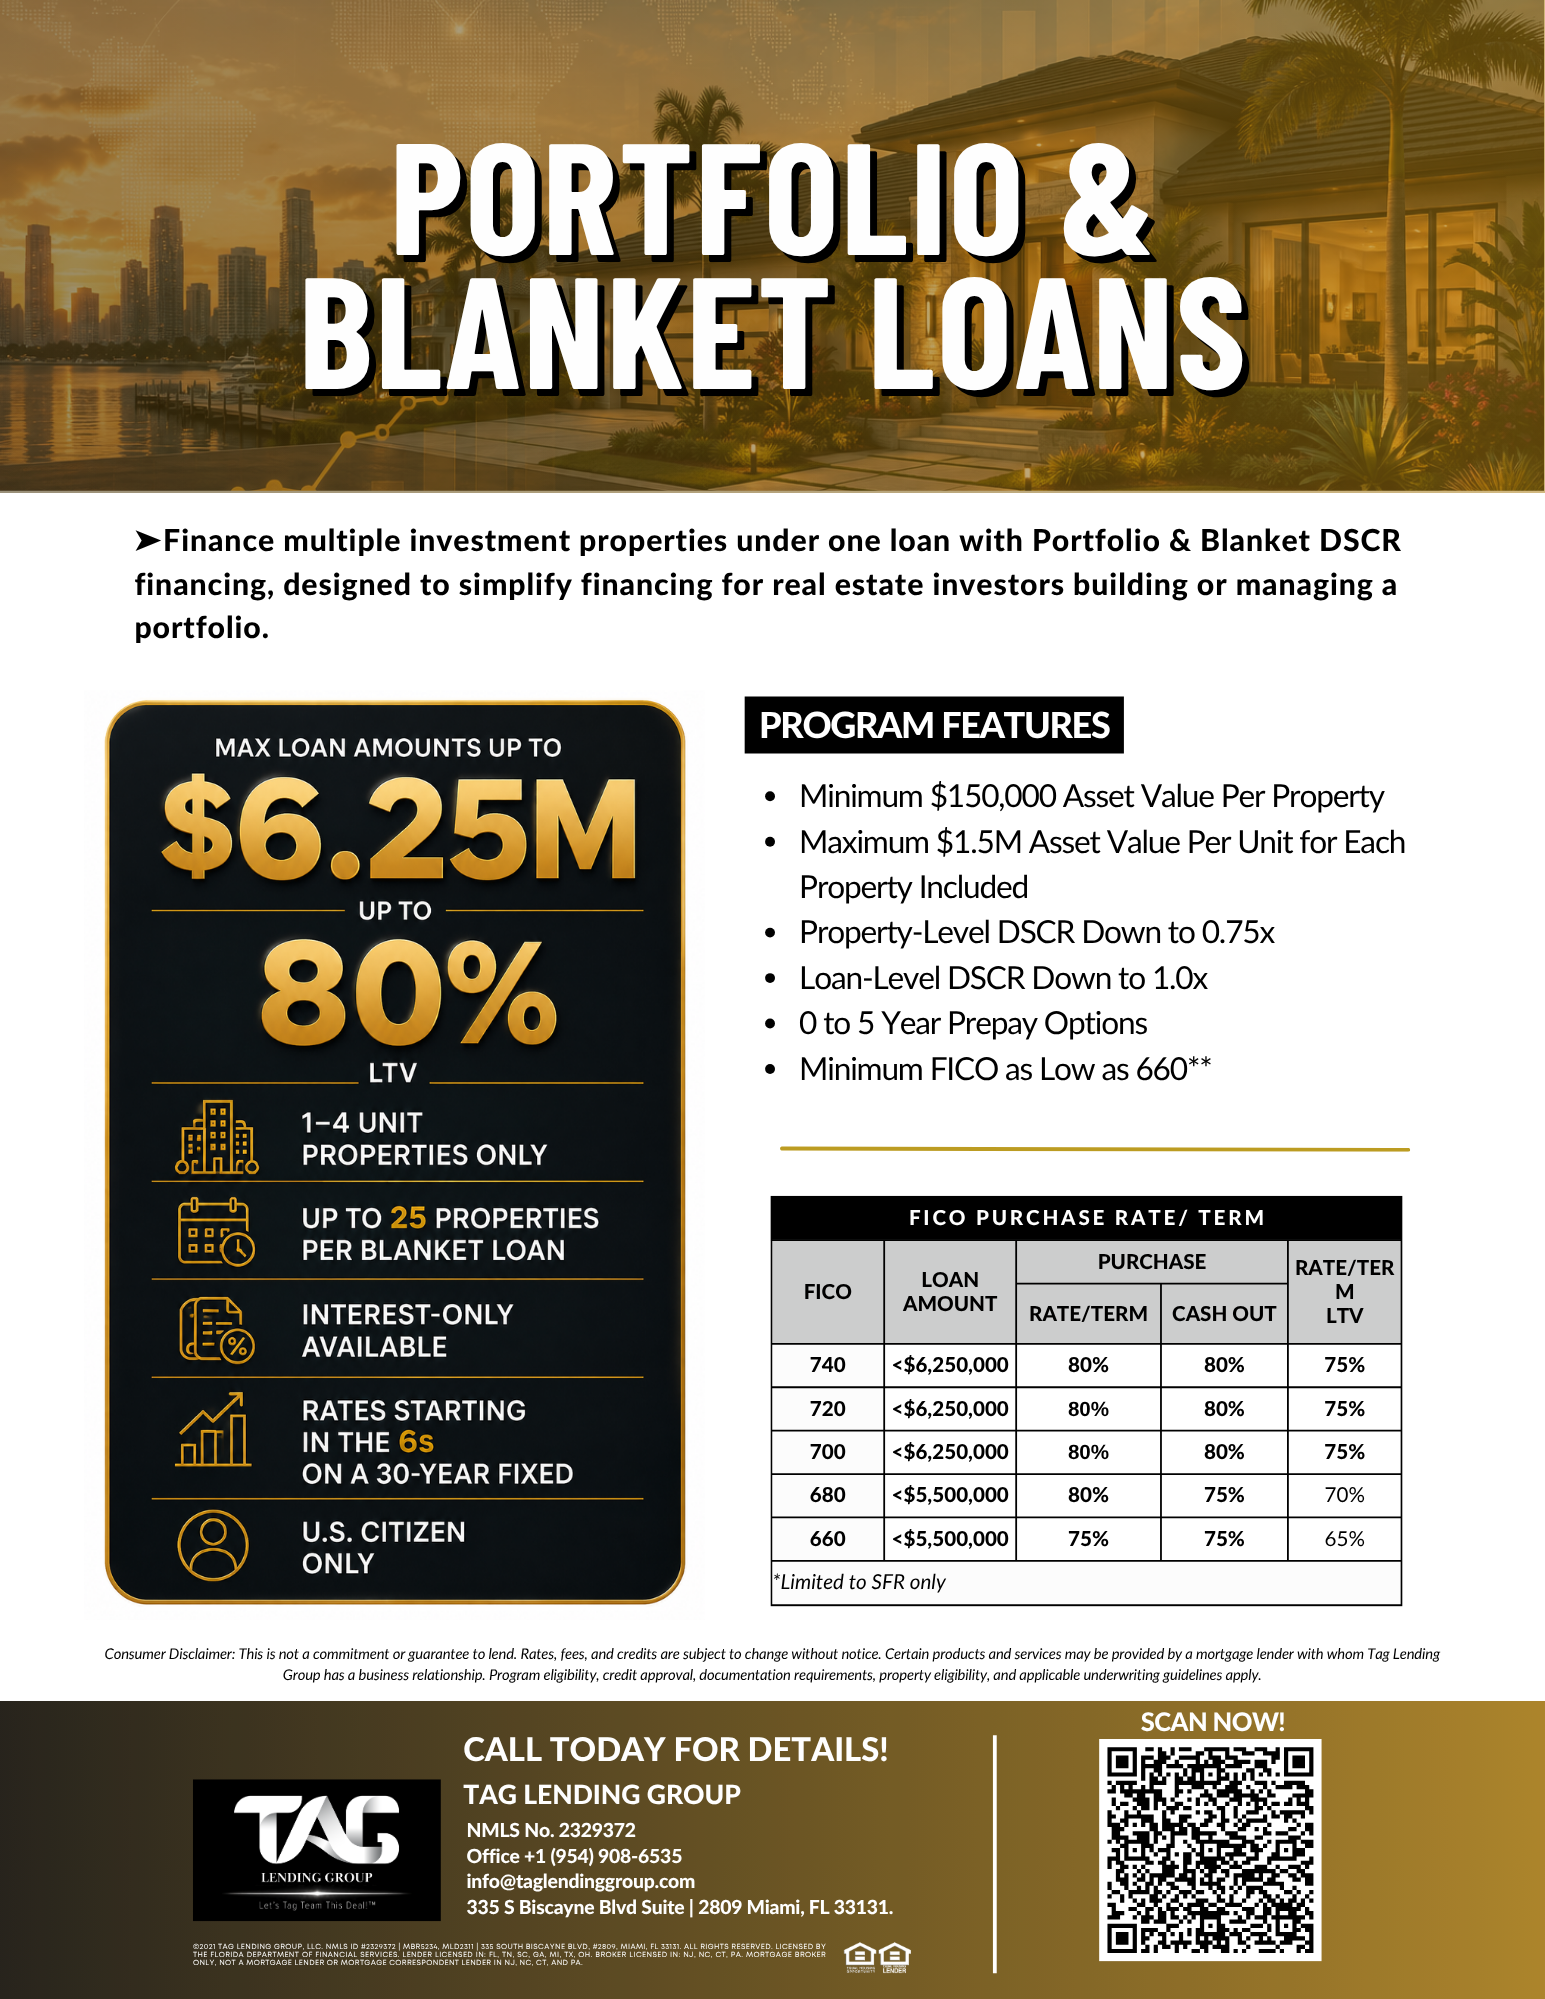
Preview the loan program sheet and download the full program details instantly.
Access the co-branded version to share this program with your clients and Co-Org Loan partners.
Connect with a loan officer to review your portfolio and get clear guidance on the best financing structure for your scenario.
Connect To A Loan OfficerQuick answer: A portfolio or blanket loan lets real estate investors finance multiple rental properties under one loan, qualified on rental income instead of personal income. TAG's cross-collateral DSCR structure offers up to 80% LTV, a 700 minimum FICO and loan amounts up to $6.25M, subject to underwriting and investor guidelines. Last reviewed: November 2026.
A single mortgage secured by more than one property, so investors can finance or refinance a group of rentals in one closing instead of several separate loans.
The cross-collateral DSCR structure offers up to 80% LTV, a 700 minimum FICO and loan amounts up to $6.25M. Final limits depend on the investor, property mix and borrower profile.
Generally no. DSCR-based portfolio loans qualify on the properties' rental income, though credit, assets and reserves are still reviewed.
Yes, closing in an LLC or other entity is available on many programs. Entity documents and guarantor requirements apply.
A standard DSCR loan covers one property. A blanket loan covers several under one note. See TAG's DSCR investor program for single-property options.
Yes. Licensed brokers can submit files through TAG's wholesale channel in the states where TAG is licensed as a lender. No approval or closing date is guaranteed.
DSCR = Monthly Rent ÷ Monthly PITIA (principal, interest, taxes, insurance and HOA). A 1.00 ratio means the rent covers the full payment. Example: $2,900 rent ÷ $2,900 PITIA = 1.00. Above 1.00, the property cash flows. Below 1.00? Most of our investors go as low as a 0.75 DSCR, and No-Ratio programs are available when the rent doesn't need to cover the payment.
A signed long-term lease.
The appraiser's market rent schedule (Form 1007).
Short-term rental income (Airbnb, VRBO and similar), based on rental history or market data, depending on the investor.
Your investing experience affects which rent source and minimum ratio an investor accepts. First-time investors may need a 1.00 or higher.
Add a partner or family member to title or your LLC and qualify using their credit.
No ownership seasoning required with some of our investors. Others require 6–12 months of ownership before a cash-out.
Close in your LLC, with no tax returns, W-2s or pay stubs.
Minimum 620 credit score. Foreign national programs do not require a U.S. credit score.
Do you own an investment property today?
Yes shows how to turn that equity into your next properties. No goes straight to the purchase calculator.
A DSCR cash-out refinance replaces your current loan with a larger one, typically up to 75–80% of the appraised value depending on the investor.
The difference between the new loan and your current balance, less closing costs, comes back to you as cash.
That cash becomes the down payment, closing costs and reserves on one or more income-producing properties.
Each new purchase can be financed with a DSCR loan that qualifies on that property's rent and can close in your LLC.
Choose a property that rents for at least its full payment, or close to it.
We use the lease, the appraiser's 1007 market rent or short-term rental data instead of tax returns.
DSCR purchases can start at 15% down with some investors. TAG recommends 25% down so the property cash flows and to avoid Loan-Level Price Adjustments (LLPAs) that apply when rent does not cover the payment.
Close as an individual or in your LLC, then repeat on the next one.
Enter your own numbers to see a hypothetical illustration. TAG Lending Group does not quote rates on this page: enter an interest rate assumption to see payments, cash flow and DSCR. Your loan officer will give you actual terms for your scenario.
As little as 15% down with some investors. TAG recommends 25% down to cash flow and avoid Loan-Level Price Adjustments (LLPAs) when rent does not cover the payment.
Closing costs are estimated for you at 3% (low) to 5% (high).
Estimated cash out
–After 3–5% closing costsAdditional properties
–Properties controlled
–Total monthly rent
–Est. net monthly cash flow
–DSCR per new property
–Loan amount
–Est. cash to close
–Principal & interest
–Total PITIA
–DSCR
–Est. monthly cash flow
–Before vs. after (monthly)
Enter your name, email and phone to get a PDF of these numbers you can text to yourself or save.
Your numbers from our proprietary Roadmap to Homeownership® Roadmap Tracker. Tell us where to send it, then text it to yourself or save it.
A TAG loan officer may reach out to walk through your scenario. Hypothetical illustration only, not a rate quote or commitment to lend.
Hypothetical illustration for educational purposes only. Not an offer, a rate quote or a commitment to lend. Results depend entirely on the assumptions entered and do not include vacancy, repairs, management, capital expenses or changes in rent, taxes, insurance or value. Payments shown are principal and interest on the selected loan term (30 years unless changed), or interest only if selected; actual programs, terms, LTV limits, reserves, minimum DSCR and closing costs vary by investor. Minimum 620 credit score; foreign national programs do not require a U.S. credit score. Business-purpose investment property financing only. Investing in real estate involves risk, including loss of equity. Consult your own tax, legal and financial advisors. TAG Lending Group, LLC, NMLS #2329372. Equal Housing Opportunity.