NON-WARRANTABLE CONDO PROGRAM

Expanded financing solutions for condos that fall outside traditional lending guidelines

Loan Programs

Non-Warrantable Condo Program

A flexible mortgage solution for borrowers purchasing or refinancing condo properties that may not meet traditional warrantable condo guidelines.

Program Overview

The Non-Warrantable Condo Program is built for borrowers who need financing on condo properties that may not qualify under traditional agency condo requirements. This program helps provide a path forward for eligible condo projects with unique characteristics, expanded investor concentration, commercial space considerations, litigation concerns, or other factors that can make standard approval more difficult.

Program Features

↗

Financing available for eligible non-warrantable condo properties.

↗

Can support qualified purchase and refinance transactions.

↗

Designed for condo projects that may not meet traditional agency requirements.

↗

May help with properties affected by investor concentration or project-specific limitations.

↗

Provides an alternative path when standard condo financing is not available.

↗

Offers more flexibility for borrowers buying or refinancing unique condo properties.

Why Choose This Program?

↗

Helps borrowers move forward with condo properties that do not fit standard guidelines.

↗

A strong option for buyers interested in unique or complex condo projects.

↗

Can provide financing access where traditional lenders may decline the project.

↗

Supports borrowers navigating condo eligibility challenges.

↗

Creates more opportunity for condo purchases and refinances in specialized markets.

↗

Gives loan officers another solution for hard-to-place condo scenarios.

Who This Program Is Great For?

↗

Borrowers purchasing an eligible non-warrantable condo.

↗

Condo buyers whose property does not meet traditional warrantable guidelines.

↗

Clients interested in condo projects with unique approval challenges.

↗

Borrowers refinancing a condo that may be considered non-warrantable.

↗

Clients who were turned away by traditional condo financing options.

↗

Borrowers needing a flexible solution for complex condo project eligibility.
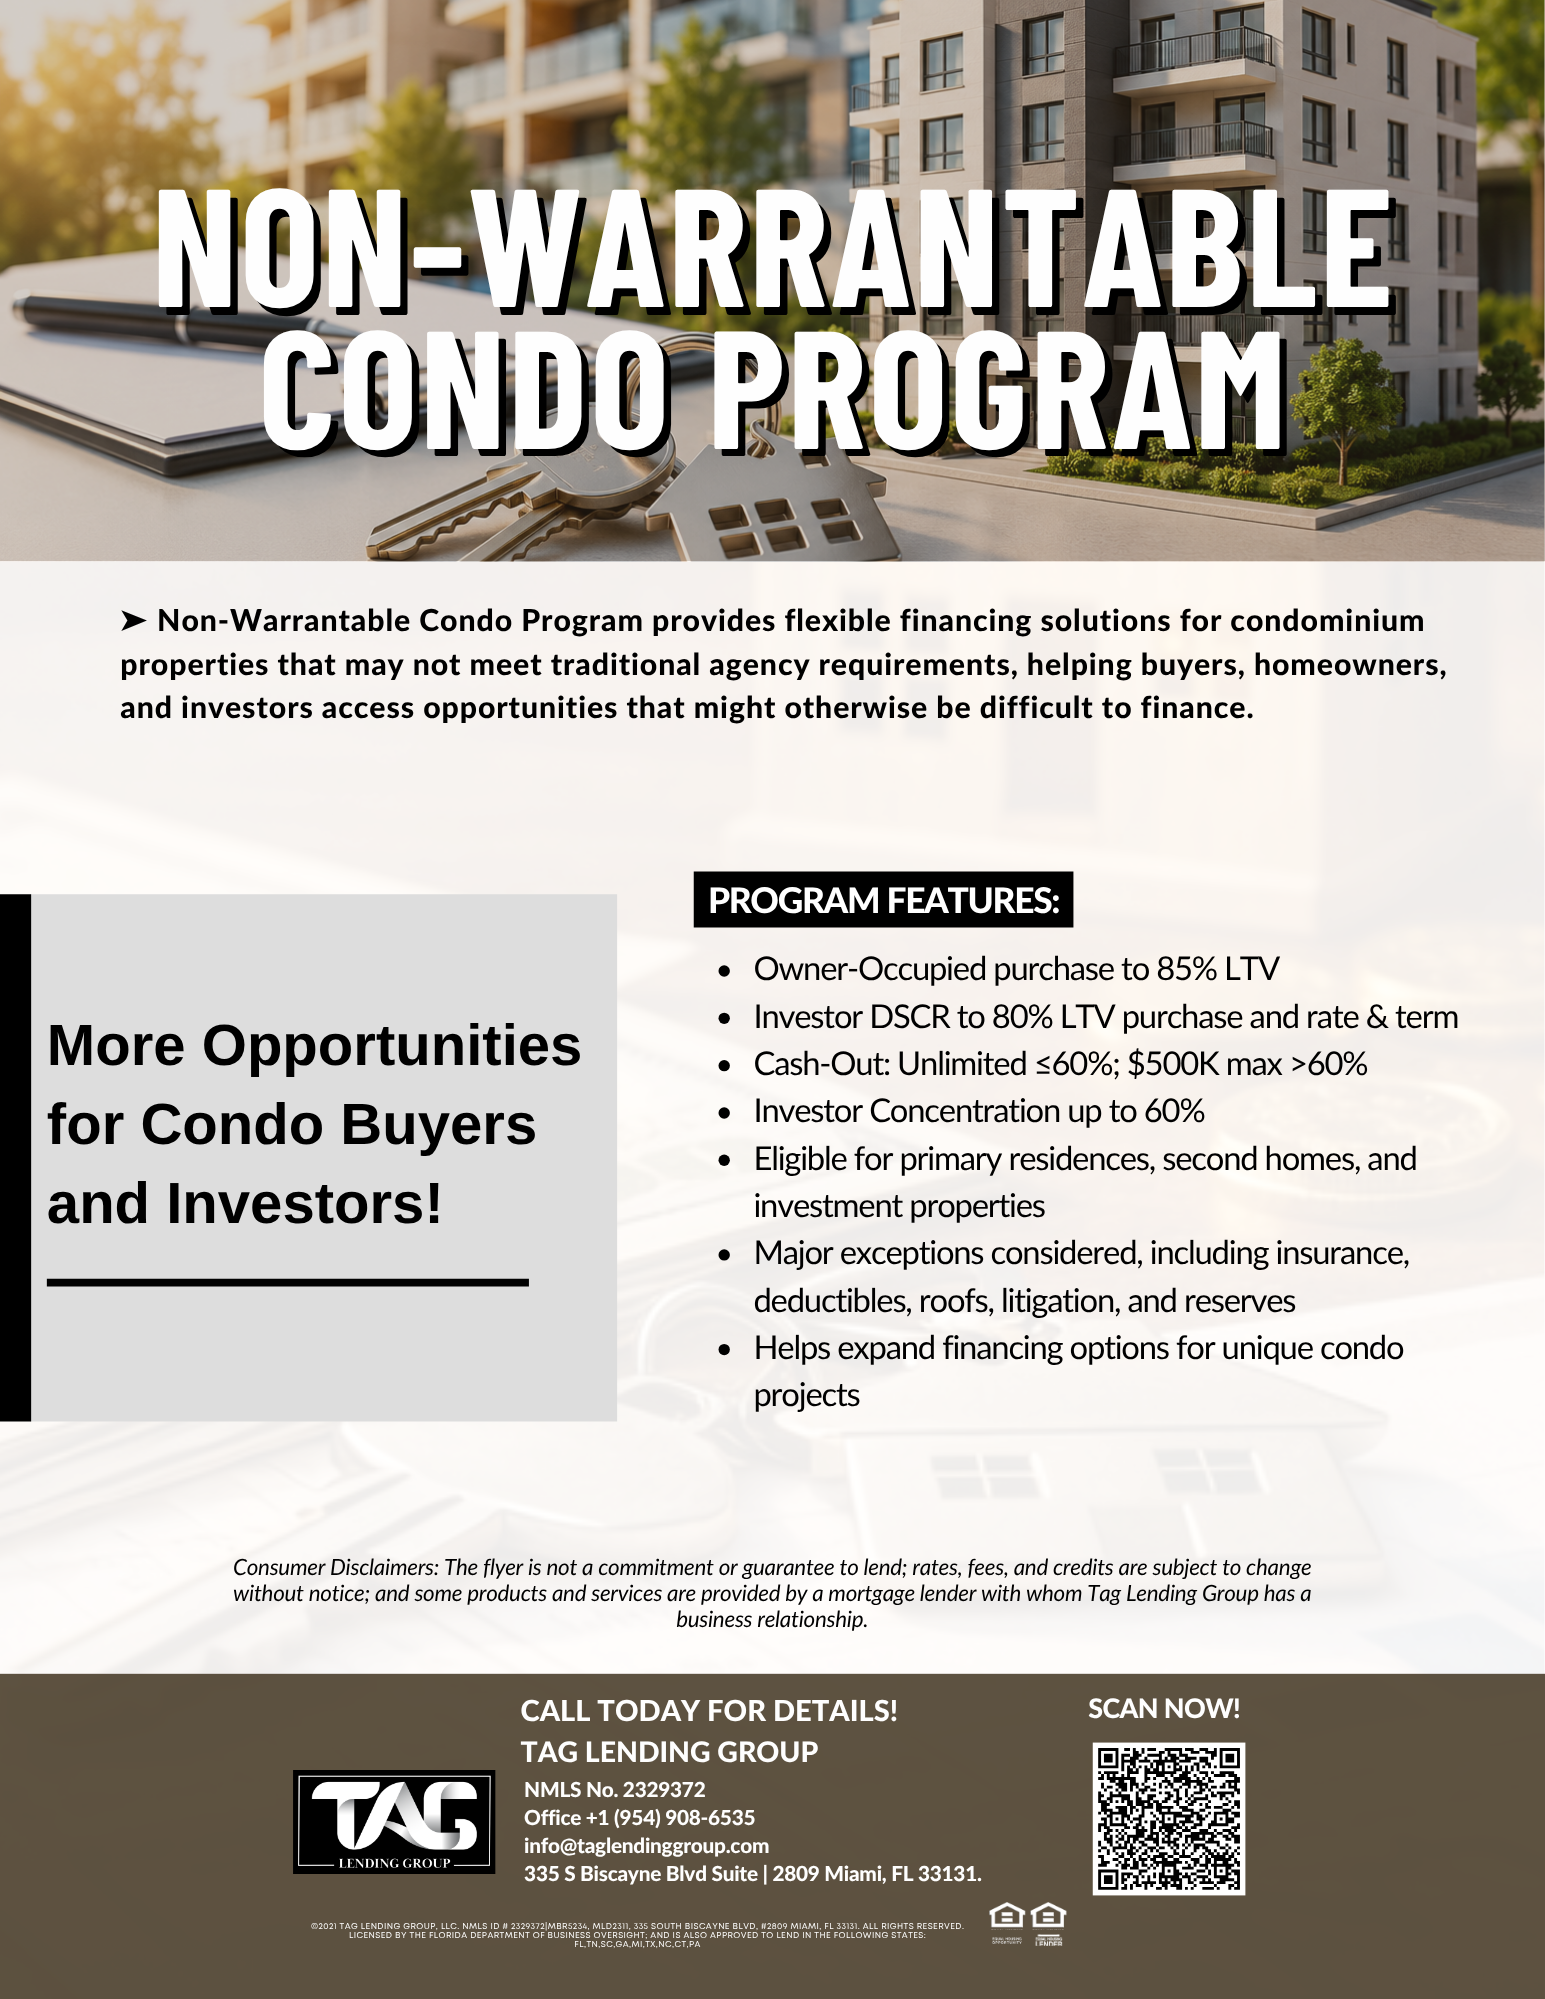
Download Loan Program

Preview the loan program sheet and download the full program details instantly.

Co-Brand Loan Program

Access the co-branded version to share this program with your clients and referral partners.

Need Help Structuring a Non-Warrantable Condo Loan?

Connect with a loan officer to review your scenario and get clear guidance on the best next step.

Connect To A Loan Officer
×

⭐ Our Google Reviews

Geraldine ⭐⭐⭐⭐⭐ I had the absolute pleasure of working with Tag Lending Group and can't say enough about the incredible experience...
Jaelyn ⭐⭐⭐⭐⭐ Vera was extremely helpful during our home buying process. The whole team made it so smooth and stress-free...
Logan ⭐⭐⭐⭐⭐ Anthony was fantastic and informative. They made my tricky situation look easy and worked hand in hand with me...
Some additional information in one line
Non-Warrantable Condo FAQ

Non-warrantable condo questions, answered

Miami condo deals live or die on the building. Here's what buyers, agents and brokers ask most.

What is a non-warrantable condo?

A non-warrantable condo is in a building that doesn't meet Fannie Mae or Freddie Mac guidelines, so it can't be financed with a standard conventional loan. Common reasons include high investor concentration, one owner holding too many units, pending litigation, too much commercial space, short-term rental activity, incomplete construction, or budget, reserve or insurance issues.

Can you finance a non-warrantable condo?

Yes. Portfolio and Non-QM programs are designed for non-warrantable buildings, subject to building review and program guidelines.

How do I know if a condo building is warrantable?

The lender reviews the condo questionnaire, HOA budget, insurance, reserves and any litigation. Start by searching our Approved Condo List before your client writes an offer.

How do Florida's condo safety laws affect financing?

Florida's post-2022 condo laws require milestone structural inspections and structural integrity reserve studies for many buildings. A building's inspection results, reserve funding and special assessments can affect whether it can be approved for financing.

Can investors buy a non-warrantable condo with a DSCR loan?

Often, yes. Many DSCR programs allow non-warrantable condos, and some allow closing in an LLC, subject to guidelines. See Miami Jumbo Condo & LLC Loans.

Can mortgage brokers place non-warrantable condo loans with TAG?

Yes. Licensed brokers can submit non-warrantable and condotel files through TAG's wholesale channel in the states where TAG is licensed as a lender.

General information only, not a commitment to lend. All loans are subject to credit approval, underwriting, property eligibility and program guidelines. Programs and availability may change without notice. TAG Lending Group, LLC · NMLS #2329372 · Equal Housing Opportunity.