Asset Utilization Program
A flexible financing solution designed to help qualified borrowers use eligible assets instead of traditional employment income to qualify.
Program Overview
The Asset Utilization Program allows qualified borrowers to use eligible assets as a qualifying income source. This program is designed for borrowers with strong asset positions who may not qualify through traditional employment income documentation.
Program Features
Qualify using eligible assets instead of traditional employment income.
Designed for borrowers with significant savings, investments, or retirement assets.
Provides an alternative documentation path for qualified borrowers.
Can support eligible purchase, refinance, and cash-flow planning scenarios.
Why Choose This Program?
Helps qualified borrowers leverage verified assets for mortgage qualification.
A strong solution for retirees, self-employed clients, and high-net-worth borrowers.
Offers flexibility when traditional income documentation is not the best fit.
Gives borrowers another path to financing based on overall financial strength.
Who This Program Is Great For?
Borrowers with strong liquid assets but limited traditional employment income.
Retirees who want to qualify using savings, investments, or retirement funds.
Self-employed borrowers with significant assets and non-traditional income profiles.
High-net-worth borrowers seeking flexible qualification options.
Clients whose financial strength is better reflected through assets.
Borrowers who need an alternative to standard income documentation.
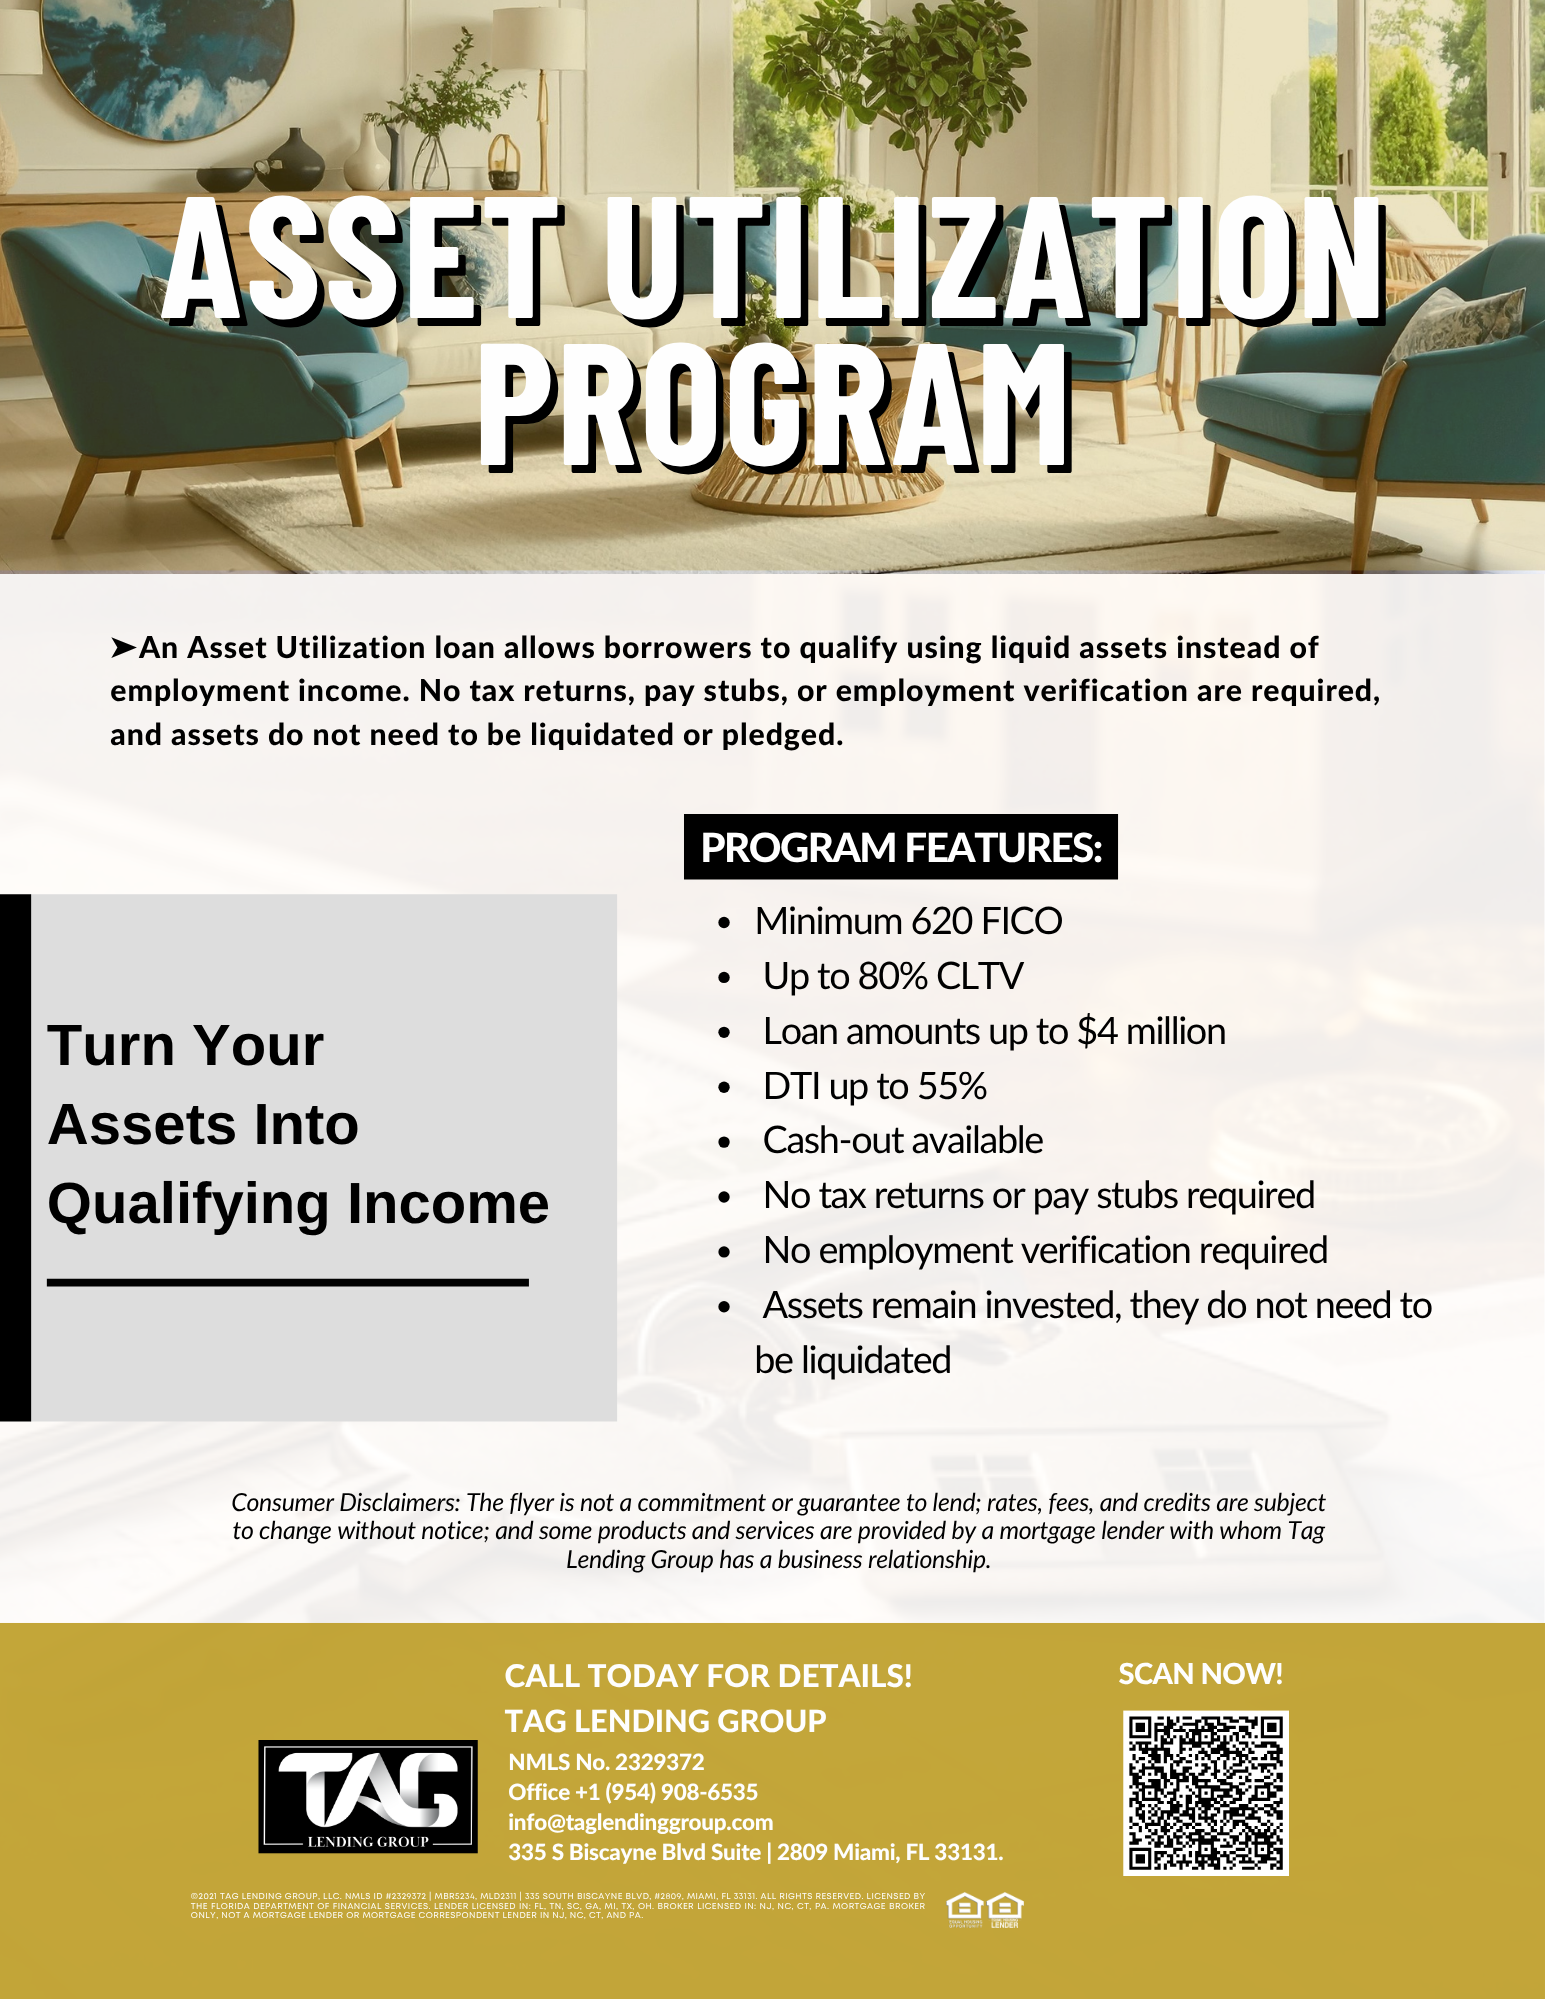
Download Loan Program
Preview the loan program sheet and download the full program details instantly.
Co-Brand Loan Program
Access the co-branded version to share this program with your clients and Co-Org Loan partners.
Need Help Structuring an Asset Utilization Loan?
Connect with a loan officer to review your scenario and explore the best financing strategy for your goals.
Connect To A Loan Officer