1099 ONLY PROGRAM

Commission income shouldn’t stop your homeownership goals

Loan Programs

1099 Only

Designed for self-employed borrowers, independent contractors, and commission-based earners who want a more flexible path to financing using 1099 income instead of traditional tax returns.

Program Overview

A flexible loan solution for borrowers with non-traditional income. The 1099 Only program allows qualified clients to use their 1099 forms for income qualification without requiring tax returns, creating a simpler and more practical path to financing.

Program Features

↗

Qualify using 1099 income instead of traditional tax returns.

↗

No tax returns required for income qualification.

↗

Financing available up to $8,000,000 for eligible borrowers.

↗

Standard scenarios start at 20% down, with up to 90% LTV available on qualifying scenarios.

↗

Requires a minimum two-year self-employment history.

↗

Available for primary residences, second homes, and investment properties.

Why Choose This Program?

↗

Built for self-employed individuals and independent contractors with non-traditional income.

↗

Helps borrowers qualify using the income documents they actually receive.

↗

Offers a simpler path when tax returns do not reflect true earning power.

↗

Supports a wide range of property and occupancy scenarios.

↗

Ideal for freelancers, consultants, and commission-based professionals.

↗

Provides more flexibility than many traditional income documentation programs.

Who This Program Is Great For?

↗

Self-employed borrowers with at least a two-year work history.

↗

Independent contractors paid through 1099 forms.

↗

Freelancers and consultants with strong income but non-traditional documentation.

↗

Commission-based earners seeking flexible financing options.

↗

Borrowers purchasing or refinancing a primary, second home, or investment property.

↗

Clients who want an alternative to traditional tax-return-based qualification.
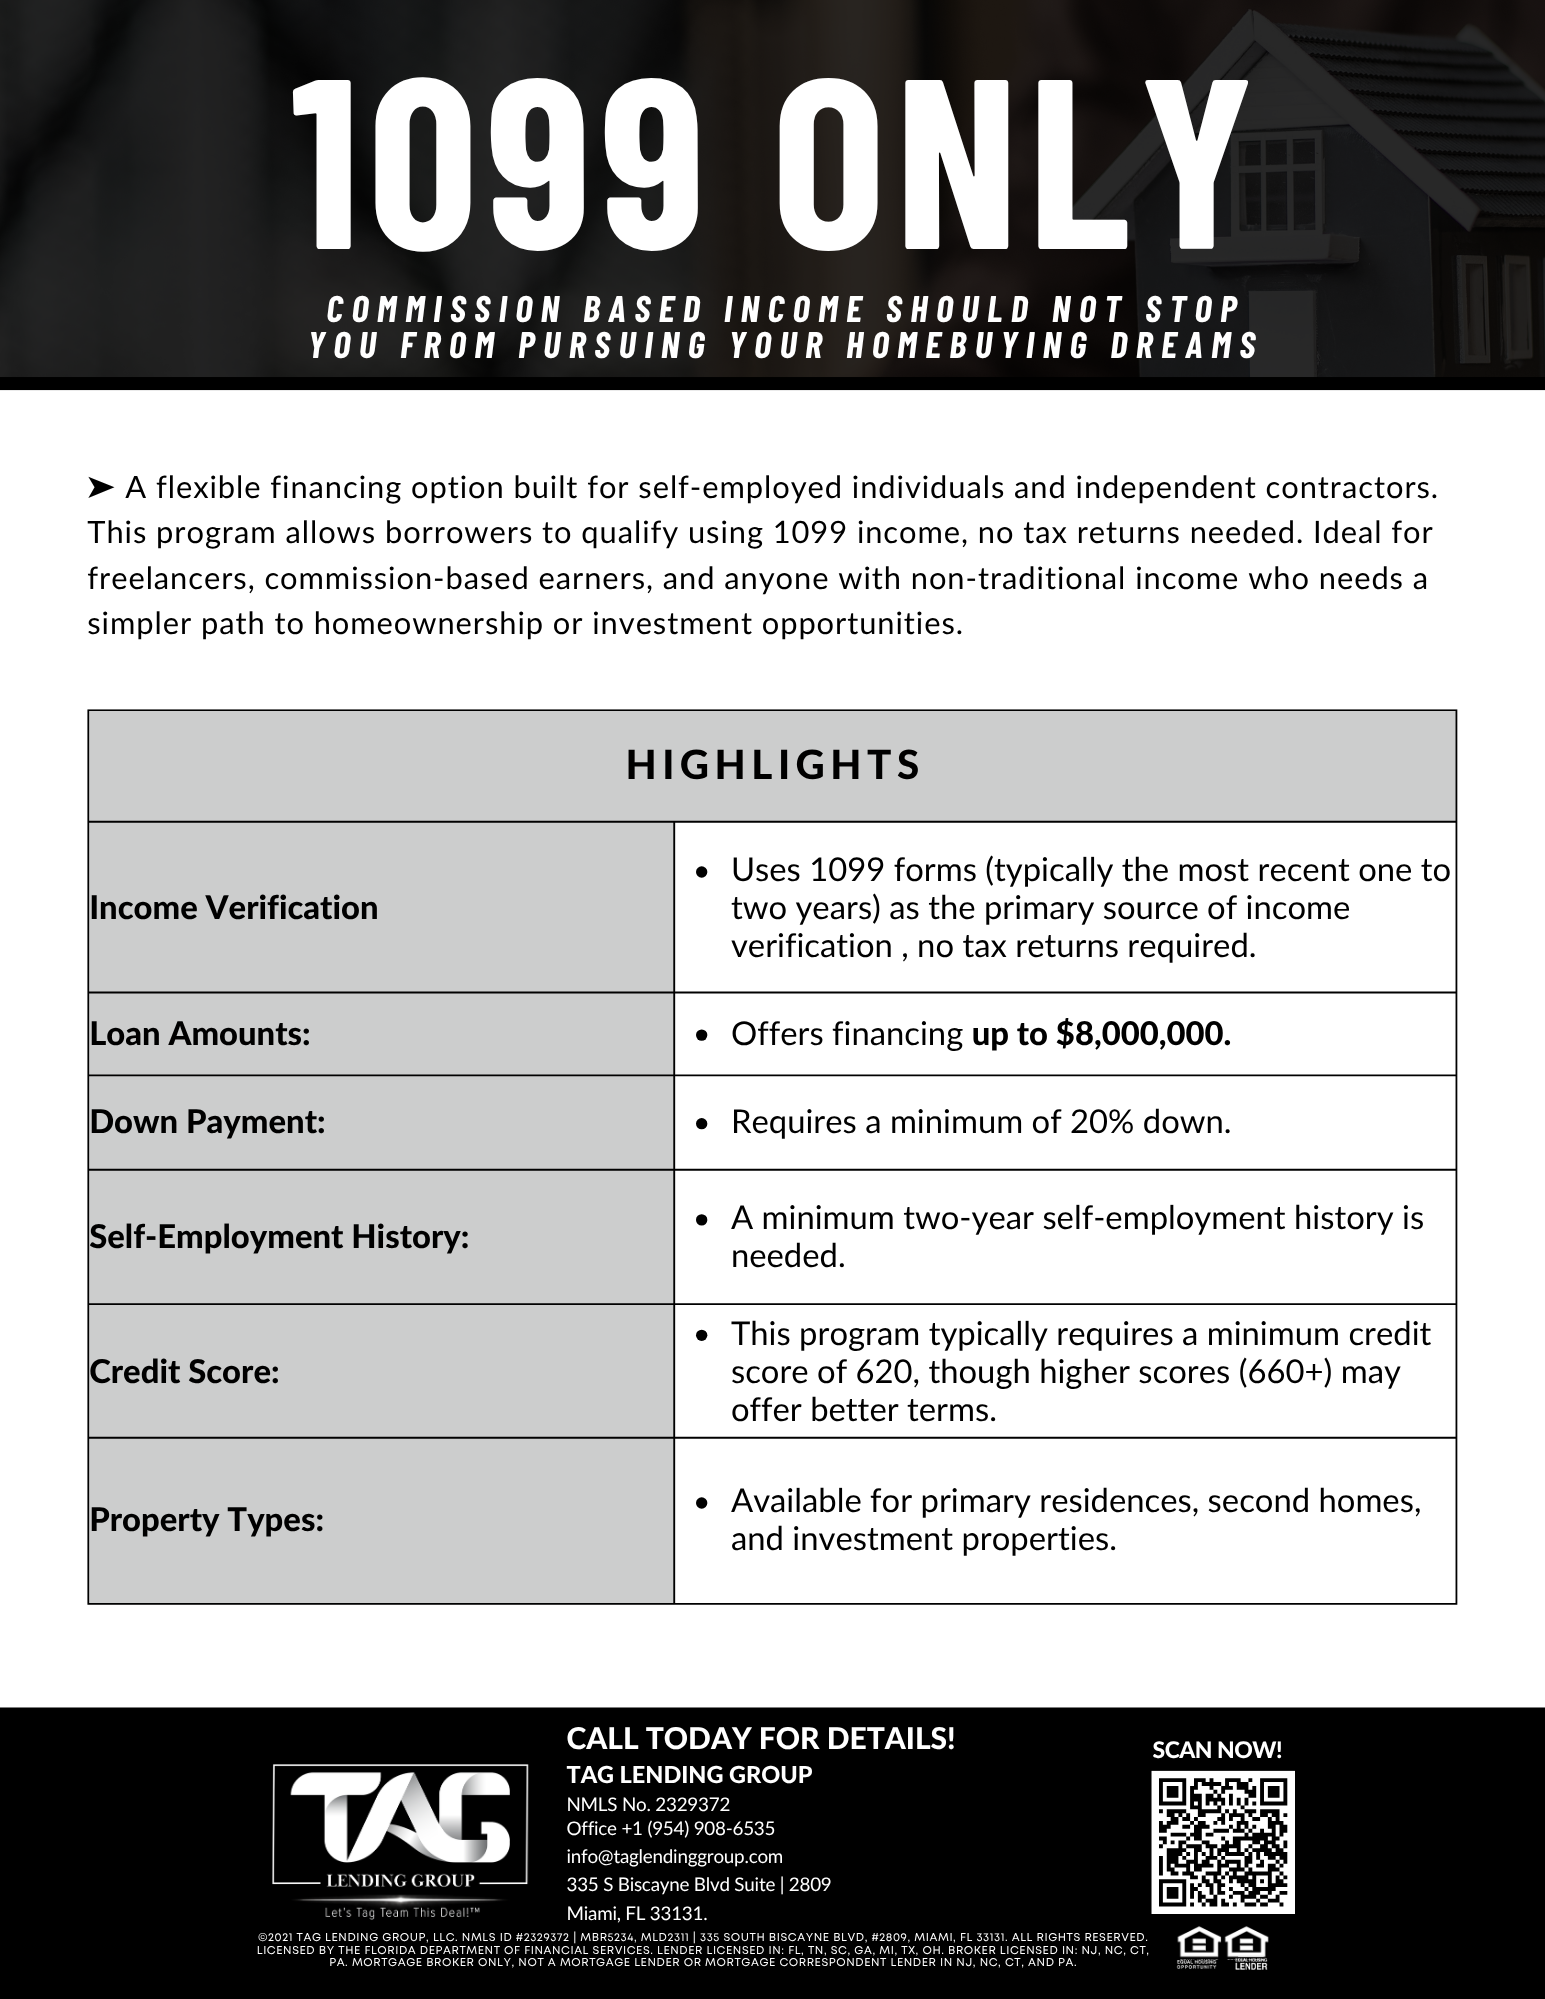
Download Loan Program

Preview the loan program sheet and download the full program details instantly.

Co-Brand Loan Program

Access the co-branded version to share this program with your clients and Co-Org Loan partners.

Need Help Structuring a 1099 Only Loan?

Connect with a loan officer to review your scenario and get clear guidance on the best next step.

Connect To A Loan Officer

1099 Loans at a Glance

Quick answer: A 1099 loan is a non-QM mortgage that qualifies self-employed borrowers on 1099 income instead of full tax returns. TAG's program offers up to 90% LTV, a 620 minimum FICO and loan amounts up to $8M, subject to underwriting and investor guidelines. Last reviewed: November 2026.

90%
Max LTV
620
Min. FICO
$8M
Max loan amount
1099s
No full tax returns

More 1099 Loan Details

  • Income documented with 1099 forms, typically one or two years, by program
  • Primary residence, second home and investment property options, by program
  • Two-year self-employment history in the same line of work, subject to guidelines
  • Available to licensed brokers through TAG's wholesale channel in TAG's lender states
  • Loan terms, LTV and eligibility vary by investor, occupancy and loan size
×

⭐ Our Google Reviews

Geraldine ⭐⭐⭐⭐⭐ I had the absolute pleasure of working with Tag Lending Group and can't say enough about the incredible experience...
Jaelyn ⭐⭐⭐⭐⭐ Vera was extremely helpful during our home buying process. The whole team made it so smooth and stress-free...
Logan ⭐⭐⭐⭐⭐ Anthony was fantastic and informative. They made my tricky situation look easy and worked hand in hand with me...
1099 Loan FAQ

1099-only mortgage questions, answered

For independent contractors and commission earners paid on 1099s.

What is a 1099-only mortgage?

A 1099-only mortgage is a Non-QM loan that qualifies borrowers using their 1099 forms instead of full tax returns.

Who qualifies for a 1099-only loan?

Independent contractors, real estate agents, gig workers, consultants and other borrowers paid on 1099s, typically with a history of 1099 income in the same line of work, subject to guidelines.

How is income calculated on a 1099 loan?

Usually from one or two years of 1099s, often with an expense factor applied. The exact method varies by program.

Do I need to provide tax returns?

Generally, no. 1099 programs typically don't require full personal tax returns, though lenders still review credit, assets and reserves.

What if I'm self-employed but don't get 1099s?

A bank statement loan may be a better fit. It qualifies you using deposits on your bank statements.

Can mortgage brokers place 1099 loans with TAG?

Yes. Licensed brokers can submit 1099 and other Non-QM files through TAG's wholesale channel in the states where TAG is licensed as a lender.

Can Florida independent contractors get a mortgage with only 1099 income?

Often yes. Florida contractors, real estate agents, consultants and gig workers can qualify using 1099 forms instead of full tax returns, through select investor programs. TAG Lending Group is a licensed mortgage lender in Florida (NMLS #2329372) and reviews the 1099 history and line of work before submission.

Can Florida Realtors paid on 1099 use this program to buy a home or investment property?

Yes. Real estate agents paid on 1099 are a common fit. 1099 programs are available for primary residences, second homes and investment properties, by program. If 1099s don't fit, bank statement and P&L options are also available.

What are the LTV, credit score and loan amount limits for a 1099 loan?

TAG's 1099 program offers up to 90% LTV, a 620 minimum FICO and loan amounts up to $8M. Final terms depend on the investor, occupancy, loan size and underwriting review.

How long do I need to be self-employed to qualify?

Programs typically look for a history of self-employment in the same line of work, commonly two years, with 1099 income documented for one or two years. Guidelines vary by investor.

Can I use a 1099 loan for an investment property?

Yes. Many 1099 programs allow second homes and investment properties as well as primary residences, subject to program rules. Investors can also review DSCR options that qualify on property cash flow.

How is a 1099 loan different from a bank statement or P&L loan?

1099 loans use 1099 forms as the income source. Bank statement loans use deposits, and P&L loans use a business profit and loss statement. The best fit depends on how your income is paid and documented.

Is approval guaranteed with a 1099 loan?

Rates and terms are not quoted on this page. A licensed loan officer can review your scenario. All loans are subject to credit approval, underwriting and program guidelines, and no approval or closing date is guaranteed.

General information only, not a commitment to lend. All loans are subject to credit approval, underwriting, property eligibility and program guidelines. Programs and availability may change without notice. TAG Lending Group, LLC · NMLS #2329372 · Equal Housing Opportunity.

Non-QM Programs

Non-QM Core Flex Program

See TAG's full Non-QM lineup for self-employed, bank statement, 1099, asset-based and investor borrowers.

View Non-QM Core Flex