Run the Equity Calculator

2–8 UNIT MIXED-USE FINANCING

Flexible DSCR financing for mixed-use properties combining residential and commercial space

Loan Programs

2–8 Unit Mixed-Use Financing

A flexible DSCR financing solution for qualified real estate investors purchasing or refinancing mixed-use properties with residential and commercial units.

Program Overview

The 2–8 Unit Mixed-Use Financing program is designed for real estate investors purchasing or refinancing properties that combine residential and commercial space. Qualification can be based on the property's rental cash flow, providing a streamlined alternative to traditional personal income documentation.

Program Features

↗

Designed for eligible 2–8 unit mixed-use investment properties.

↗

Qualification may be based on rental analysis and property cash flow.

↗

Personal employment and income documentation may not be required for qualification.

↗

Available for qualified purchase and refinance transactions.

↗

Investment-property focused financing for residential and commercial mixed-use buildings.

↗

Flexible loan structures available for qualified real estate investors.

Why Choose This Program?

↗

Provides a financing path for properties that may not fit standard residential guidelines.

↗

Allows qualified investors to use the property's rental performance for qualification.

↗

Helps simplify documentation by reducing reliance on personal income qualification.

↗

Supports investors acquiring properties with both residential and commercial income.

↗

A practical financing option for experienced real estate investors expanding their portfolios.

↗

Offers greater flexibility for unique mixed-use property scenarios.

Who This Program Is Great For?

↗

Real estate investors purchasing 2–8 unit mixed-use properties.

↗

Investors refinancing properties that combine residential and commercial units.

↗

Borrowers who prefer property cash flow rather than personal income qualification.

↗

Experienced investors expanding into larger or more complex rental properties.

↗

Clients financing properties with retail, office, restaurant, or other eligible commercial space.

↗

Investors seeking flexible financing outside traditional residential loan programs.
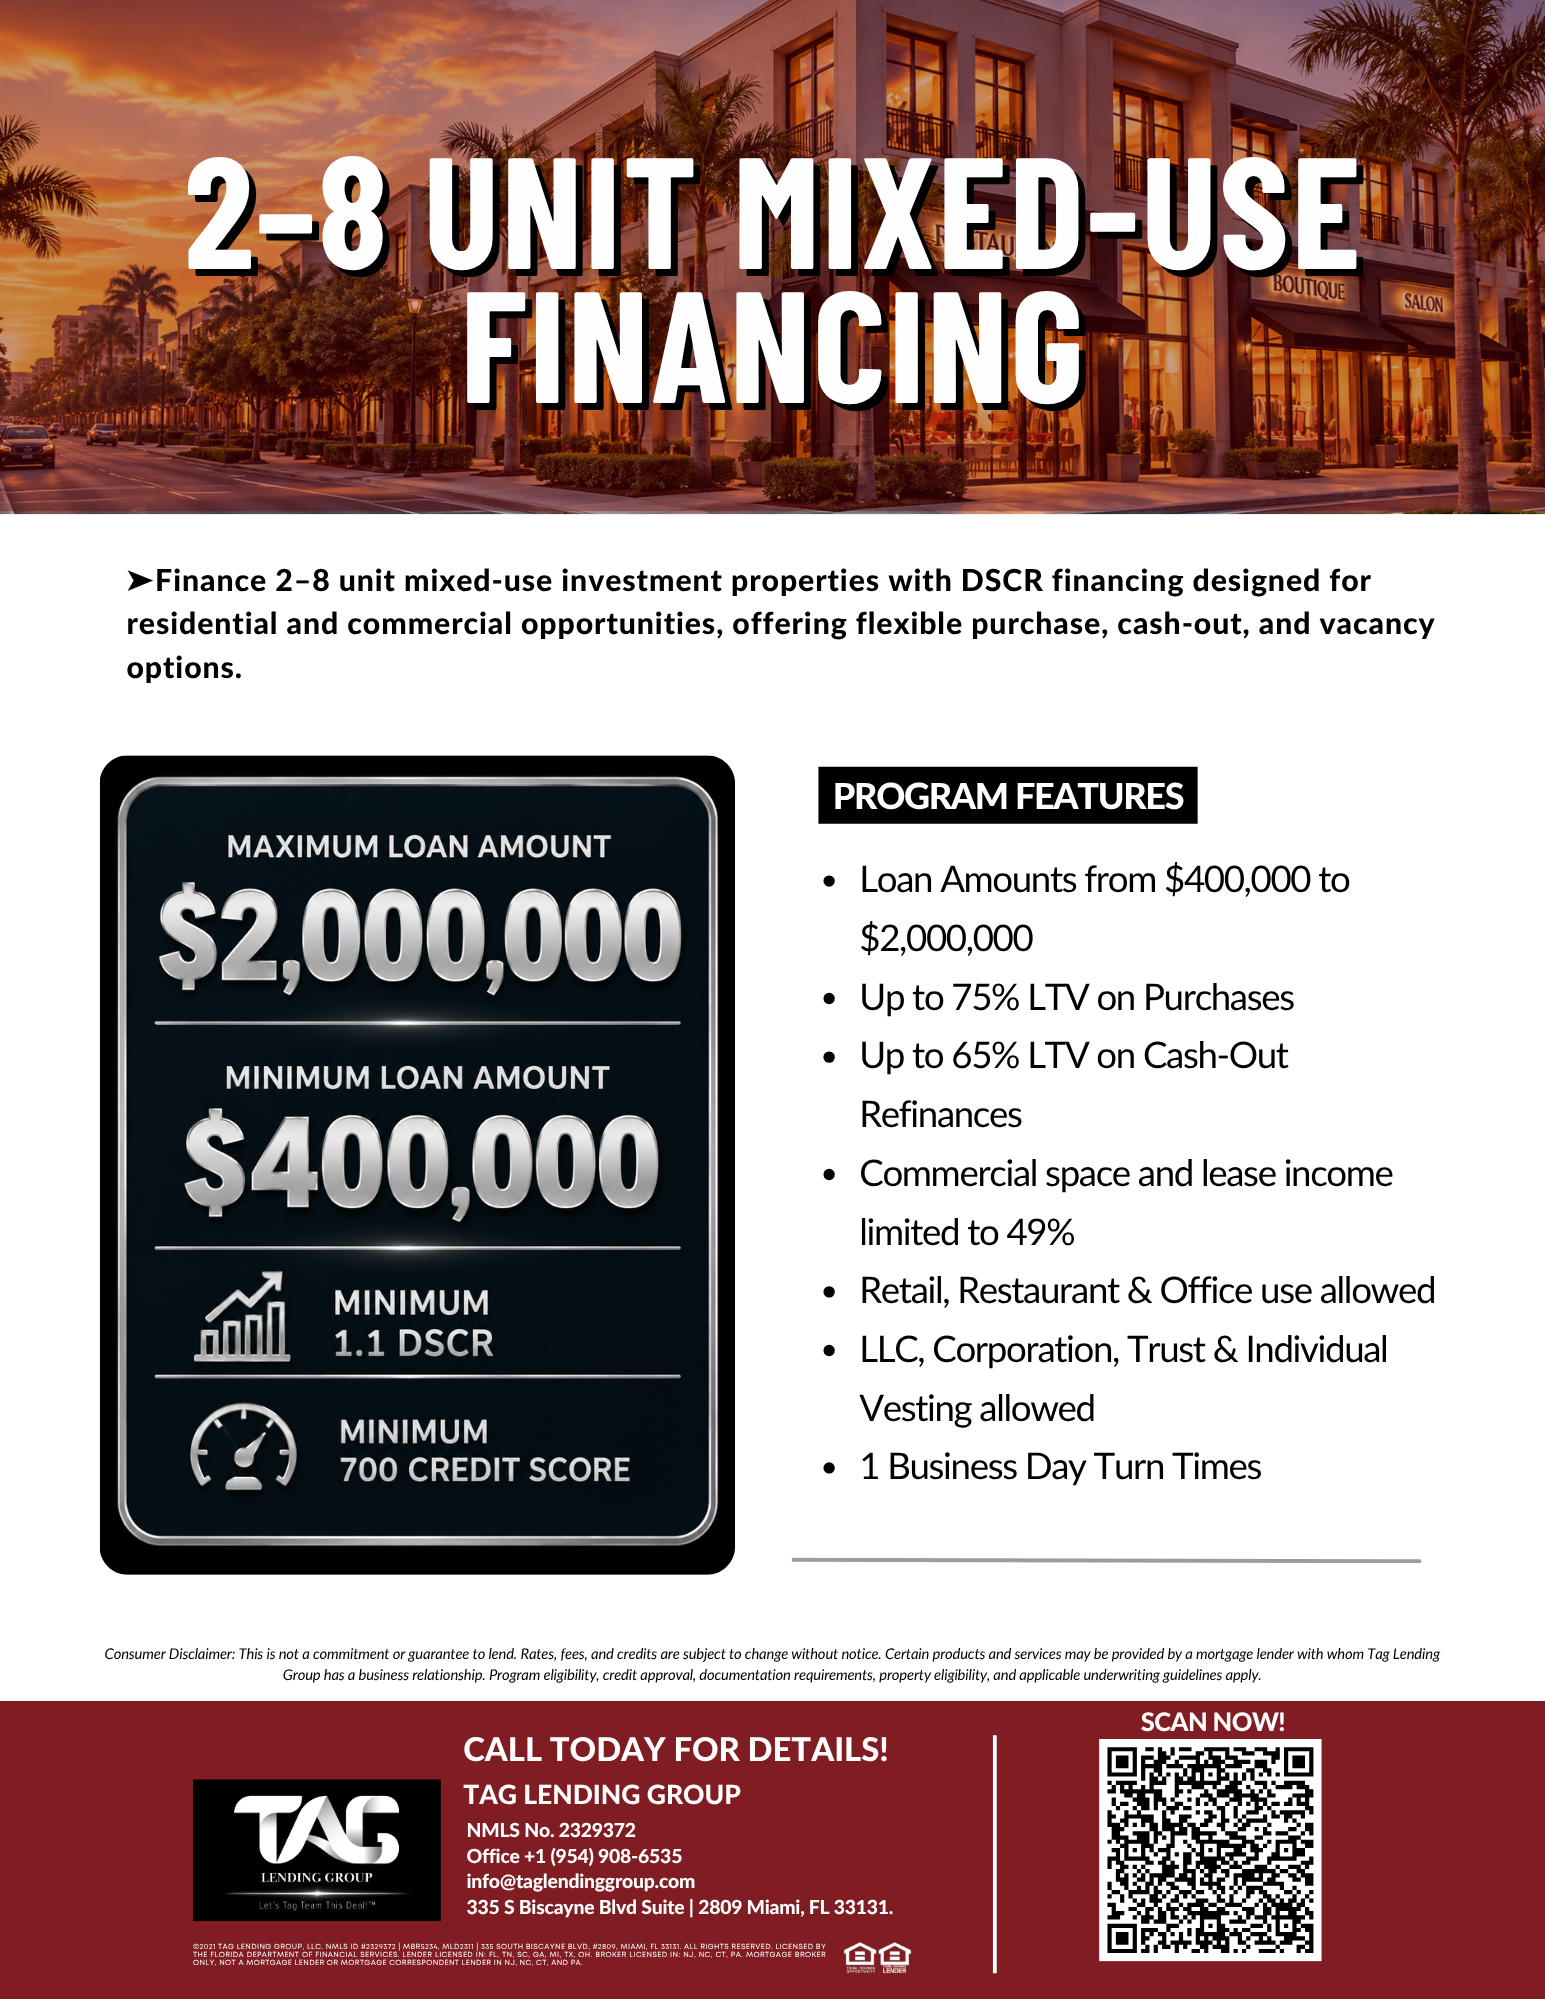
Download Loan Program

Preview the loan program sheet and download the full program details instantly.

Co-Brand Loan Program

Access the co-branded version to share this program with your clients and Co-Org Loan partners.

Need Help Structuring a 2–8 Unit Mixed-Use Loan?

Connect with a loan officer to review your scenario and get clear guidance on the best next step.

Connect To A Loan Officer

2-8 Unit and Mixed-Use Financing at a Glance

Quick answer: TAG finances 2-8 unit residential and mixed-use investment properties, qualified on the property's rental income instead of personal income. On the DSCR program, 2-4 unit properties offer up to 85% LTV, a 620 minimum FICO and loan amounts up to $3.5M, and 5-8 unit properties offer up to 75% LTV, a 700 minimum FICO and loan amounts up to $2M, subject to underwriting and investor guidelines. Last reviewed: November 2026.

85%
Max LTV, 2-4 units
75%
Max LTV, 5-8 units
$3.5M
Max loan, 2-4 units
$2M
Max loan, 5-8 units

More 2-8 Unit and Mixed-Use Details

  • 2-4 units: 620 minimum FICO. 5-8 units: 700 minimum FICO
  • Qualification is based on rental income, not personal income or tax returns
  • Closing in an LLC or other entity is available by program
  • Mixed-use eligibility, including the share of commercial space, varies by investor and is reviewed per property
  • Terms, LTV and eligibility vary by investor, occupancy, property type and loan size

2-8 Unit and Mixed-Use FAQs

Can I finance a 5-8 unit property with a DSCR loan?

Yes. TAG's DSCR program covers 5-8 unit residential properties with up to 75% LTV, a 700 minimum FICO and loan amounts up to $2M, subject to investor guidelines.

What is a mixed-use property?

A building that combines residential units with commercial space, such as apartments above a storefront. Eligibility depends on the investor and the share of commercial space.

Do I need tax returns to finance a multifamily investment property?

Generally no on DSCR programs. Qualification is based on the property's rental income, though credit, assets and reserves are still reviewed.

Can I close in an LLC?

Yes, closing in an LLC or other entity is available on many DSCR programs. Entity documents and guarantor requirements apply.

Where can I see all DSCR limits?

See TAG's DSCR investor program page, or the portfolio and blanket loan page for multiple properties under one loan.

Can mortgage brokers submit 2-8 unit loans to TAG?

Yes. Licensed brokers can submit files through TAG's wholesale channel in the states where TAG is licensed as a lender. No approval or closing date is guaranteed.

How We Calculate DSCR: The 1.00 Ratio

DSCR = Monthly Rent ÷ Monthly PITIA (principal, interest, taxes, insurance and HOA). A 1.00 ratio means the rent covers the full payment. Example: $2,900 rent ÷ $2,900 PITIA = 1.00. Above 1.00, the property cash flows. Below 1.00? Most of our investors go as low as a 0.75 DSCR, and No-Ratio programs are available when the rent doesn't need to cover the payment.

Rent We Can Use

↗

A signed long-term lease.

↗

The appraiser's market rent schedule (Form 1007).

↗

Short-term rental income (Airbnb, VRBO and similar), based on rental history or market data, depending on the investor.

↗

Your investing experience affects which rent source and minimum ratio an investor accepts. First-time investors may need a 1.00 or higher.

Flexibility That Helps You Qualify

↗

Add a partner or family member to title or your LLC and qualify using their credit.

↗

No ownership seasoning required with some of our investors. Others require 6–12 months of ownership before a cash-out.

↗

Close in your LLC, with no tax returns, W-2s or pay stubs.

↗

Minimum 620 credit score. Foreign national programs do not require a U.S. credit score.

Run Your DSCR Numbers

Do you own an investment property today?

Yes shows how to turn that equity into your next properties. No goes straight to the purchase calculator.

How the Equity-to-Portfolio Strategy Works

1

Refinance the rental you own

A DSCR cash-out refinance replaces your current loan with a larger one, typically up to 75–80% of the appraised value depending on the investor.

2

Pull out the equity

The difference between the new loan and your current balance, less closing costs, comes back to you as cash.

3

Use it as down payments

That cash becomes the down payment, closing costs and reserves on one or more income-producing properties.

4

Qualify each on its rent

Each new purchase can be financed with a DSCR loan that qualifies on that property's rent and can close in your LLC.

How a DSCR Purchase Works

1

Pick the rental

Choose a property that rents for at least its full payment, or close to it.

2

Rent qualifies the loan

We use the lease, the appraiser's 1007 market rent or short-term rental data instead of tax returns.

3

Bring down payment and reserves

DSCR purchases can start at 15% down with some investors. TAG recommends 25% down so the property cash flows and to avoid Loan-Level Price Adjustments (LLPAs) that apply when rent does not cover the payment.

4

Close in your name or LLC

Close as an individual or in your LLC, then repeat on the next one.

Equity-to-Portfolio Calculator

DSCR Purchase Calculator

Enter your own numbers to see a hypothetical illustration. TAG Lending Group does not quote rates on this page: enter an interest rate assumption to see payments, cash flow and DSCR. Your loan officer will give you actual terms for your scenario.

Property you own

Next properties

Property you want to buy

As little as 15% down with some investors. TAG recommends 25% down to cash flow and avoid Loan-Level Price Adjustments (LLPAs) when rent does not cover the payment.

Assumptions

Closing costs are estimated for you at 3% (low) to 5% (high).

Estimated cash out

–After 3–5% closing costs

Additional properties

–

Properties controlled

–

Total monthly rent

–

Est. net monthly cash flow

–

DSCR per new property

–

Loan amount

–

Est. cash to close

–

Principal & interest

–

Total PITIA

–

DSCR

–

Est. monthly cash flow

–

Before vs. after (monthly)

Enter your name, email and phone to get a PDF of these numbers you can text to yourself or save.

Hypothetical illustration for educational purposes only. Not an offer, a rate quote or a commitment to lend. Results depend entirely on the assumptions entered and do not include vacancy, repairs, management, capital expenses or changes in rent, taxes, insurance or value. Payments shown are principal and interest on the selected loan term (30 years unless changed), or interest only if selected; actual programs, terms, LTV limits, reserves, minimum DSCR and closing costs vary by investor. Minimum 620 credit score; foreign national programs do not require a U.S. credit score. Business-purpose investment property financing only. Investing in real estate involves risk, including loss of equity. Consult your own tax, legal and financial advisors. TAG Lending Group, LLC, NMLS #2329372. Equal Housing Opportunity.

×

⭐ Our Google Reviews

Geraldine ⭐⭐⭐⭐⭐ I had the absolute pleasure of working with Tag Lending Group and can't say enough about the incredible experience...
Jaelyn ⭐⭐⭐⭐⭐ Vera was extremely helpful during our home buying process. The whole team made it so smooth and stress-free...
Logan ⭐⭐⭐⭐⭐ Anthony was fantastic and informative. They made my tricky situation look easy and worked hand in hand with me...