Real estate investing often starts with recognizing the potential in a property that needs work. Whether it's updating an outdated home, renovating a distressed property, or preparing a house for resale, the right financing plays an important role in bringing an investment project to life.
For investors looking to purchase, renovate, and resell properties, the Tag Lending Group Fix & Flip Program offers short-term funding built around the needs of real estate investment projects, with construction draws available for approved renovations.
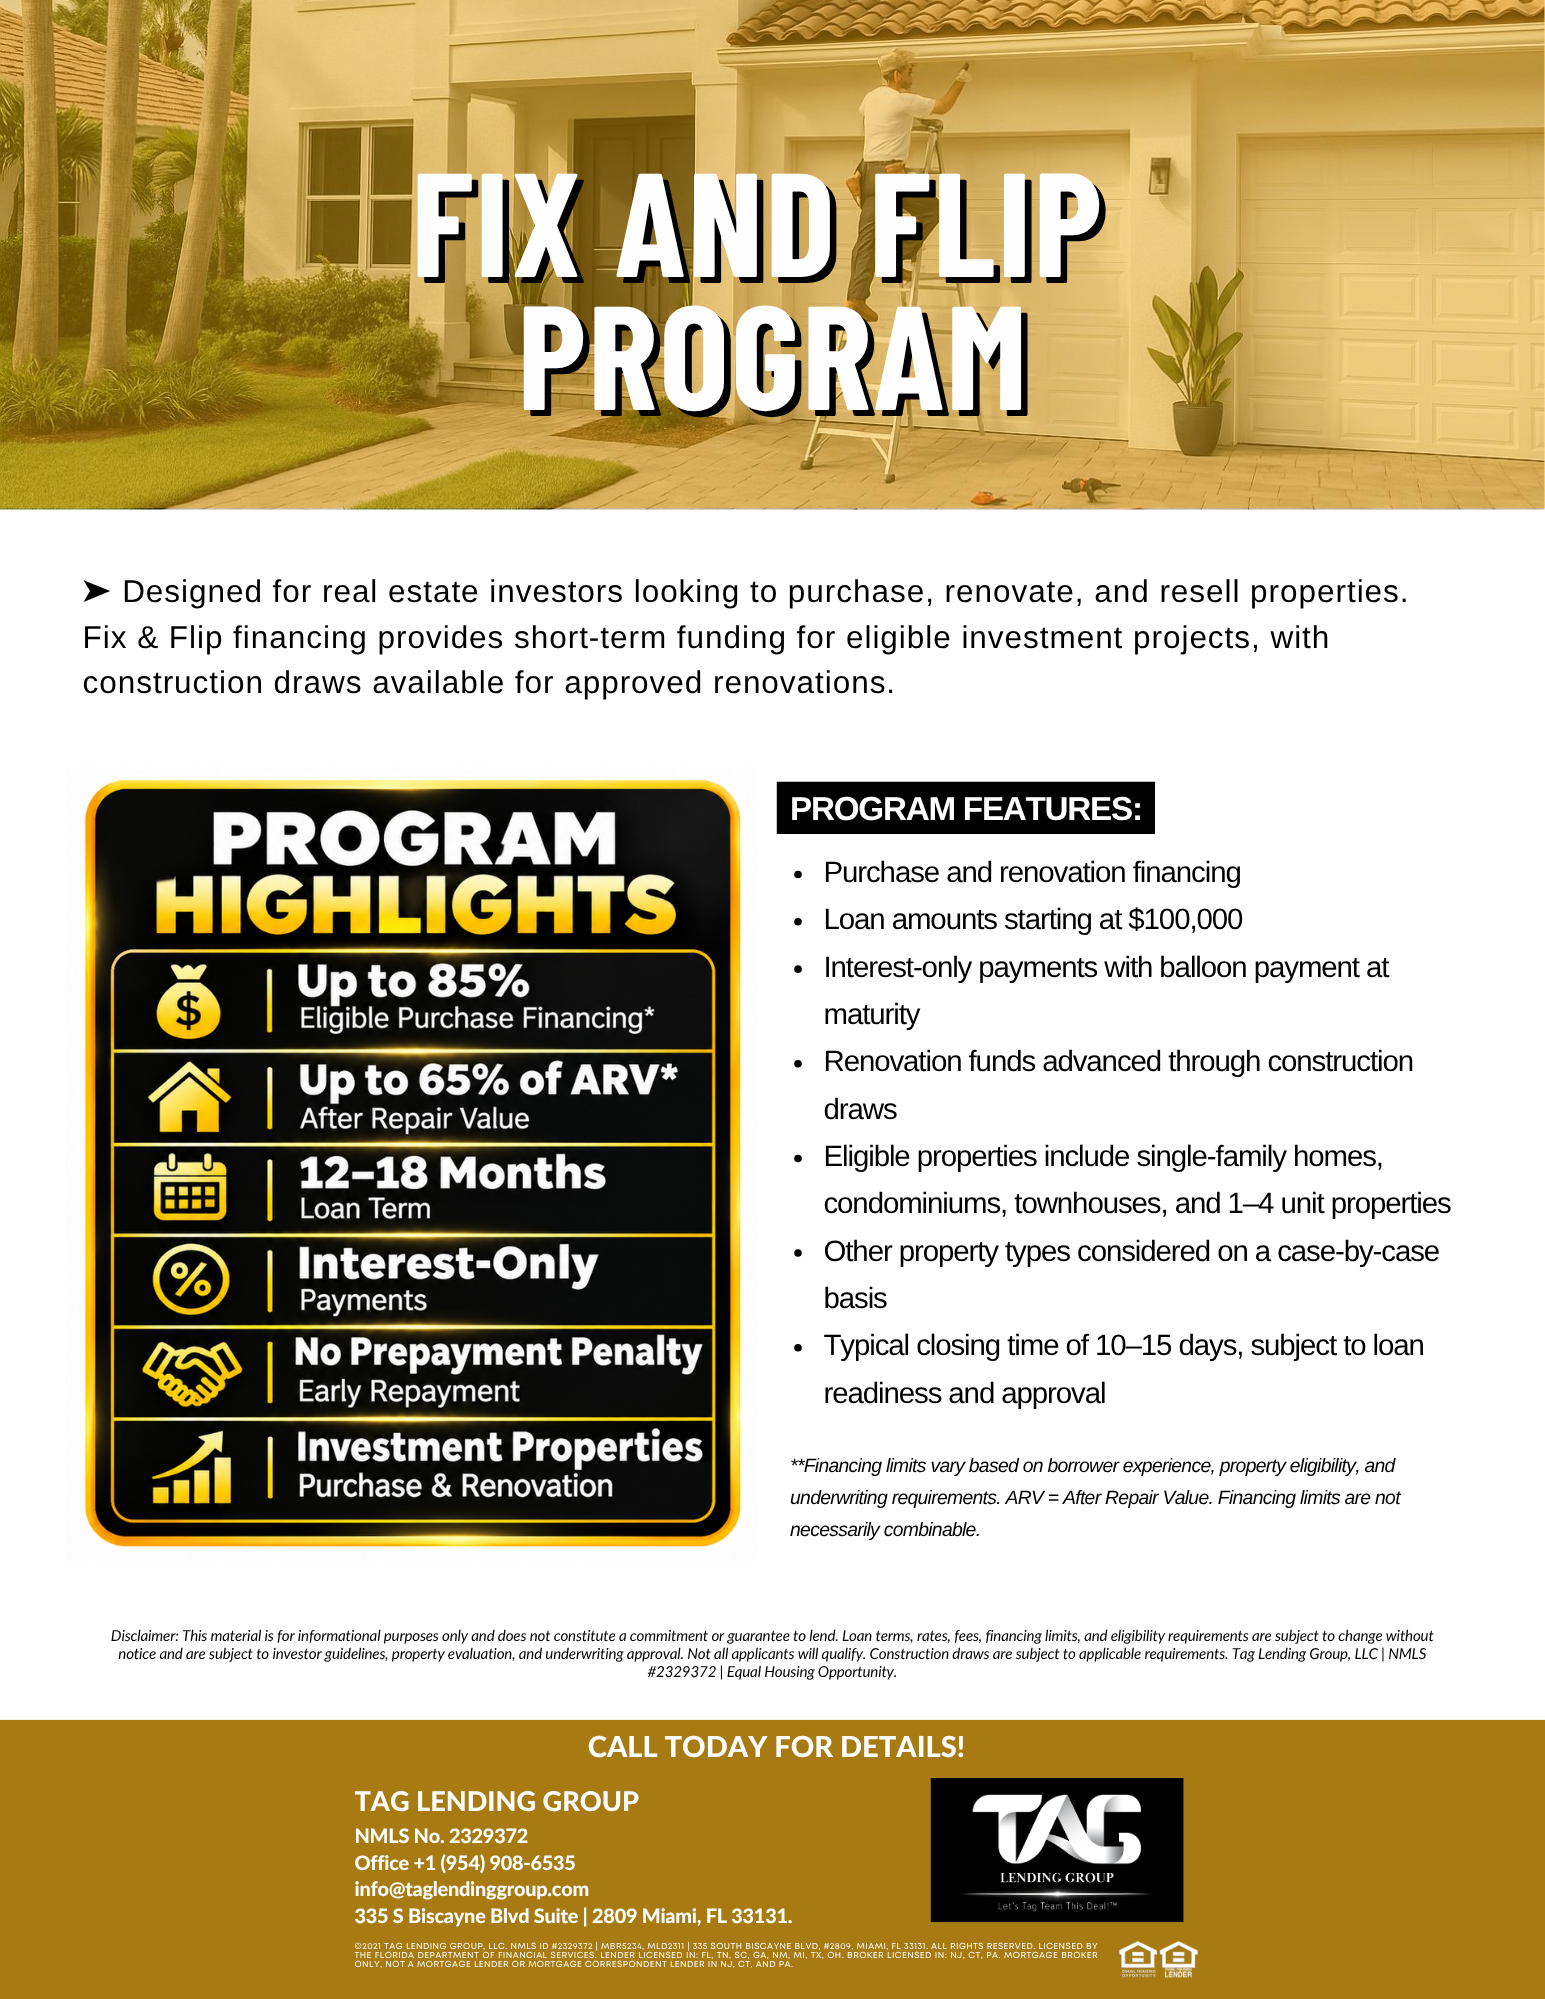
Program Highlights at a Glance
- Up to 85% eligible purchase financing*
- Up to 65% of ARV* (After Repair Value)
- 12–18 month loan terms
- Interest-only payments
- No prepayment penalty
- Loan amounts starting at $100,000
- Typical closing in 10–15 days, subject to loan readiness and approval
*Financing limits vary based on borrower experience, property eligibility, and underwriting requirements. Financing limits are not necessarily combinable.
What Is a Fix & Flip Loan?
A Fix & Flip loan is a short-term financing option for real estate investors who purchase properties with the intention of renovating and reselling them.
Unlike traditional mortgages, which are structured for long-term homeownership, Fix & Flip loans are designed for investment projects with shorter timelines. Depending on the loan structure and eligibility, financing may cover both the property purchase and approved renovation expenses.
Key Features of the Fix & Flip Program
1. Purchase and Renovation Financing
The program can finance both the acquisition and the approved renovation budget, so investors can plan the full project under one loan. Eligible purchase financing goes up to 85%, with total financing up to 65% of the property's ARV, depending on borrower experience and guidelines.
2. Short-Term Loan Structure
Loan terms range from 12 to 18 months, giving investors room to plan around their renovation and resale timeline. Loan amounts start at $100,000.
3. Interest-Only Payments
Interest-only payments help investors manage monthly carrying costs during the renovation period. A balloon payment of the remaining principal is due at maturity.
4. Renovation Funds Through Construction Draws
Approved renovation funds are advanced through construction draws as the project progresses, subject to lender requirements and inspections where applicable.
5. Multiple Eligible Property Types
The program accommodates several residential investment property types:
- Single-family homes
- Condominiums
- Townhouses
- 1–4 unit residential properties
Other property types may be considered on a case-by-case basis.
6. No Prepayment Penalty
Qualifying investors can repay the loan before maturity without an additional prepayment charge — useful when a property sells ahead of schedule.
7. Financing Based on After Repair Value (ARV)
Financing may be evaluated using the purchase price, eligible project costs, and the property's estimated After Repair Value. ARV is the estimated value of the property once the planned renovations are complete.
8. Efficient Closings
Typical closing time is 10–15 days, subject to loan readiness and approval — helping investors move on time-sensitive opportunities.
How Does Fix & Flip Financing Work?
Step 1: Identify an Investment Property
Find a property with renovation and resale potential. Evaluate the purchase price, estimated repair costs, and the local market.
Step 2: Prepare a Renovation Plan
A detailed budget and scope of work help the lender evaluate the project's financing needs and the anticipated value after improvements.
Step 3: Apply for Financing
The lender reviews the property, borrower qualifications, investment experience, renovation plan, and other underwriting requirements.
Step 4: Complete the Renovation
Once the loan closes, the renovation begins. Approved renovation funds are released through construction draws according to the lender's requirements.
Step 5: Sell or Execute the Exit Strategy
After renovations are complete, the investor may list the property for sale. Sale proceeds are used to repay the outstanding loan balance and applicable costs. Because Fix & Flip loans are short-term, a realistic exit strategy should be in place before the project begins.
Who Can Benefit From Fix & Flip Financing?
- Experienced real estate investors financing additional renovation projects
- Newer investors exploring qualifying renovation opportunities
- Renovation professionals purchasing residential properties to improve and resell
- Investors seeking short-term financing instead of a traditional long-term mortgage
Eligibility, financing limits, and loan terms vary based on borrower qualifications, investment experience, property details, and underwriting guidelines.
What Should Investors Consider Before Starting?
Successful investing takes more than finding a property with resale potential. Investors should evaluate acquisition costs, renovation expenses, property taxes, insurance, financing costs, and expected holding periods.
Unexpected repairs, construction delays, or changes in market conditions can affect profitability. A realistic renovation budget, sufficient reserves, and a clear exit strategy help investors make informed financing decisions.
For MLOs, Brokers & Realtor Partners
Have an investor client with a renovation project? Tag Lending Group works with MLO, broker, and Realtor partners to bring Fix & Flip scenarios to the table — from initial scenario review through closing. Partner compensation is available through our Co-Org Loan structure.
Ready to Finance Your Next Fix & Flip Project?
Whether it's a first investment property or the next project in a growing portfolio, understanding the financing options is an important first step. Contact Tag Lending Group to discuss the scenario.
Call: +1 (954) 908-6535
Email: info@taglendinggroup.com
Office: 335 S Biscayne Blvd, Suite 2809, Miami, FL 33131
Disclaimer: This article is for informational purposes only and does not constitute a commitment or guarantee to lend. Loan terms, rates, fees, financing limits, and eligibility requirements are subject to change without notice and are subject to investor guidelines, property evaluation, and underwriting approval. Not all applicants will qualify. Construction draws are subject to applicable requirements. Typical closing timelines are not guaranteed. Tag Lending Group, LLC | NMLS #2329372 | Equal Housing Opportunity. Lender licensed in: FL, GA, MI, NM, OH, SC, TN, TX. Broker licensed in: CT, NJ, PA — mortgage broker only, not a mortgage lender or mortgage correspondent lender in CT, NJ, and PA.