W-2 to 1099 Program
For borrowers who moved from W-2 pay to 1099 income doing the same work. Eligible borrowers may qualify using 1099 earnings without an expense factor, even without an established 1099 work history.*
Program Overview
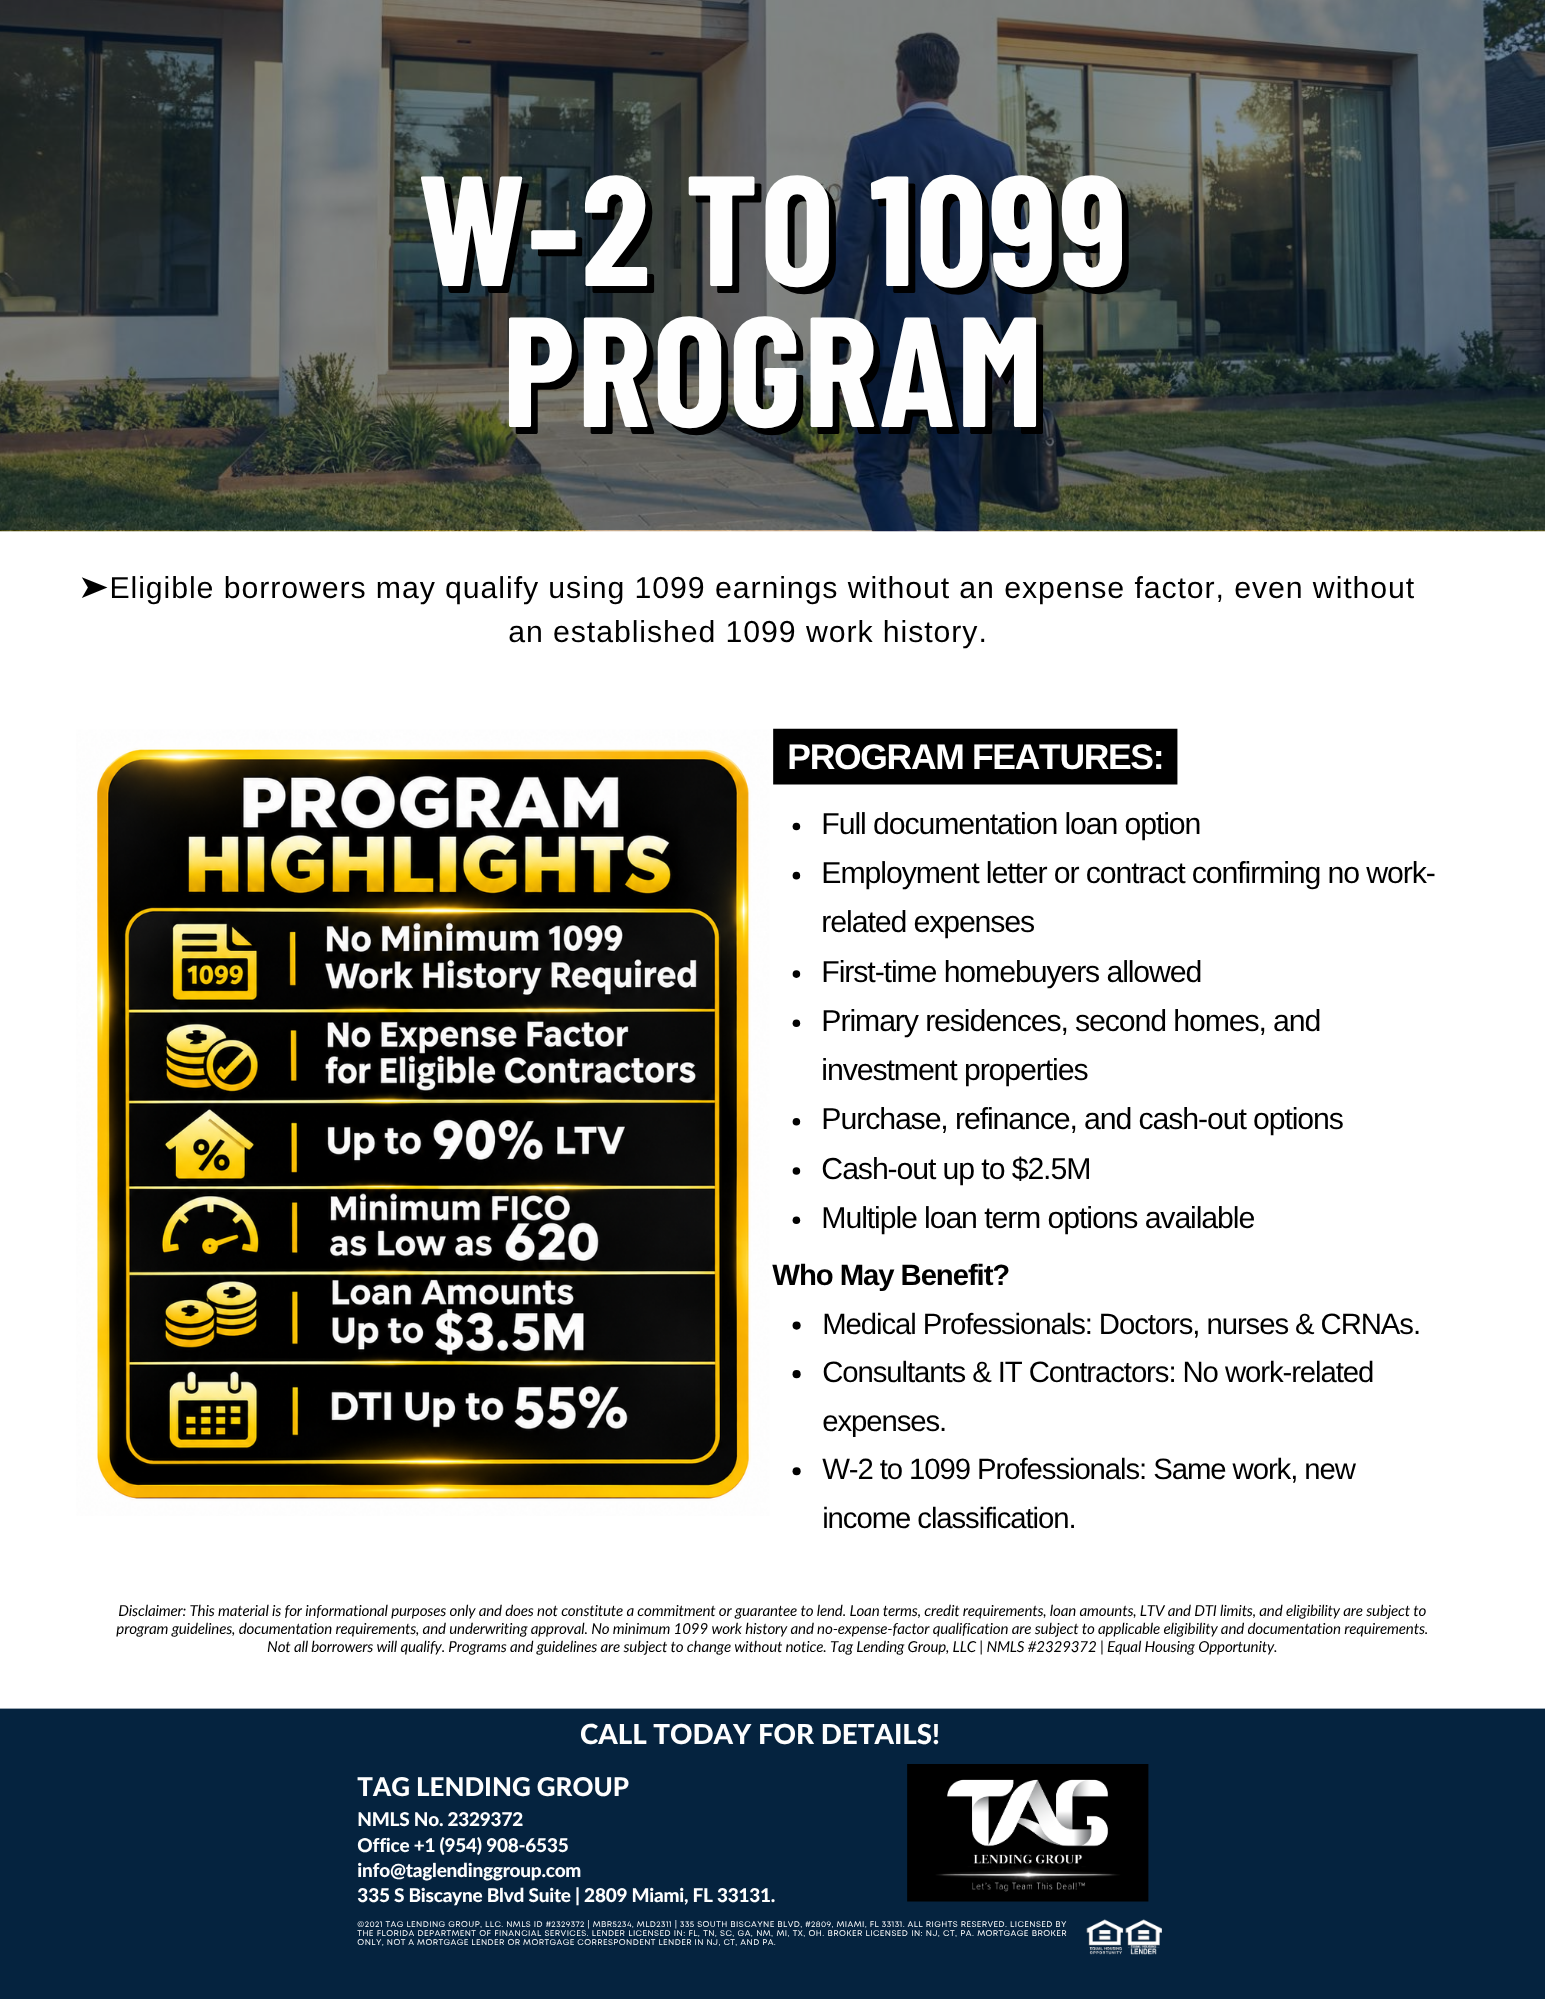
The W-2 to 1099 Program is a full documentation option for borrowers whose pay changed from W-2 wages to 1099 income while their work stayed the same. Instead of waiting to build a 1099 history, eligible borrowers may qualify using their 1099 earnings without an expense factor, supported by an employment letter or contract confirming no work-related expenses.*
Program Features
Full documentation loan option.
Employment letter or contract confirming no work-related expenses.
First-time homebuyers allowed.
Primary residences, second homes and investment properties.
Purchase, refinance and cash-out options.
Cash-out up to $2.5M.*
Multiple loan term options available.
Loan amounts up to $3.5M, up to 90% LTV and DTI up to 55%, with a minimum FICO of 620.*
Why Choose This Program?
Eligible borrowers may qualify using 1099 earnings without an expense factor.*
No established 1099 work history required for eligible borrowers.*
Built for borrowers doing the same work after a switch from W-2 to 1099 pay.
Full documentation structure, with income supported by an employment letter or contract.
Brokers and MLOs submit through our wholesale and non-delegated correspondent channels.
*No minimum 1099 work history and no-expense-factor qualification are subject to applicable eligibility and documentation requirements. Loan terms, credit requirements, loan amounts, LTV and DTI limits, and eligibility are subject to program guidelines, documentation requirements and underwriting approval.
Who This Program Is Great For?
Medical professionals: doctors, nurses and CRNAs.
Consultants and IT contractors with no work-related expenses.
W-2 to 1099 professionals: same work, new income classification.
Buyers and homeowners financing a primary residence, second home or investment property.
First-time homebuyers paid on 1099.
Brokers and MLOs with 1099 borrowers who don't yet have a 1099 history.
Download Loan Program
Preview the W-2 to 1099 program sheet and download the full program details.
Co-Brand Loan Program
Access the co-branded version to share this program with your clients and Co-Org Loan partners.
Have a W-2 to 1099 Scenario?
Send us the borrower's occupation, when the pay changed from W-2 to 1099, the employment letter or contract, property type, occupancy and loan purpose. A loan officer will review the scenario and outline next steps.
Connect To A Loan OfficerFor informational purposes only; not a commitment or guarantee to lend. Loan terms, credit requirements, loan amounts, LTV and DTI limits and eligibility are subject to program guidelines, documentation requirements and underwriting approval. No minimum 1099 work history and no-expense-factor qualification are subject to applicable eligibility and documentation requirements. Not all borrowers will qualify. Programs and guidelines are subject to change without notice. TAG Lending Group, LLC · NMLS #2329372 · Equal Housing Opportunity.