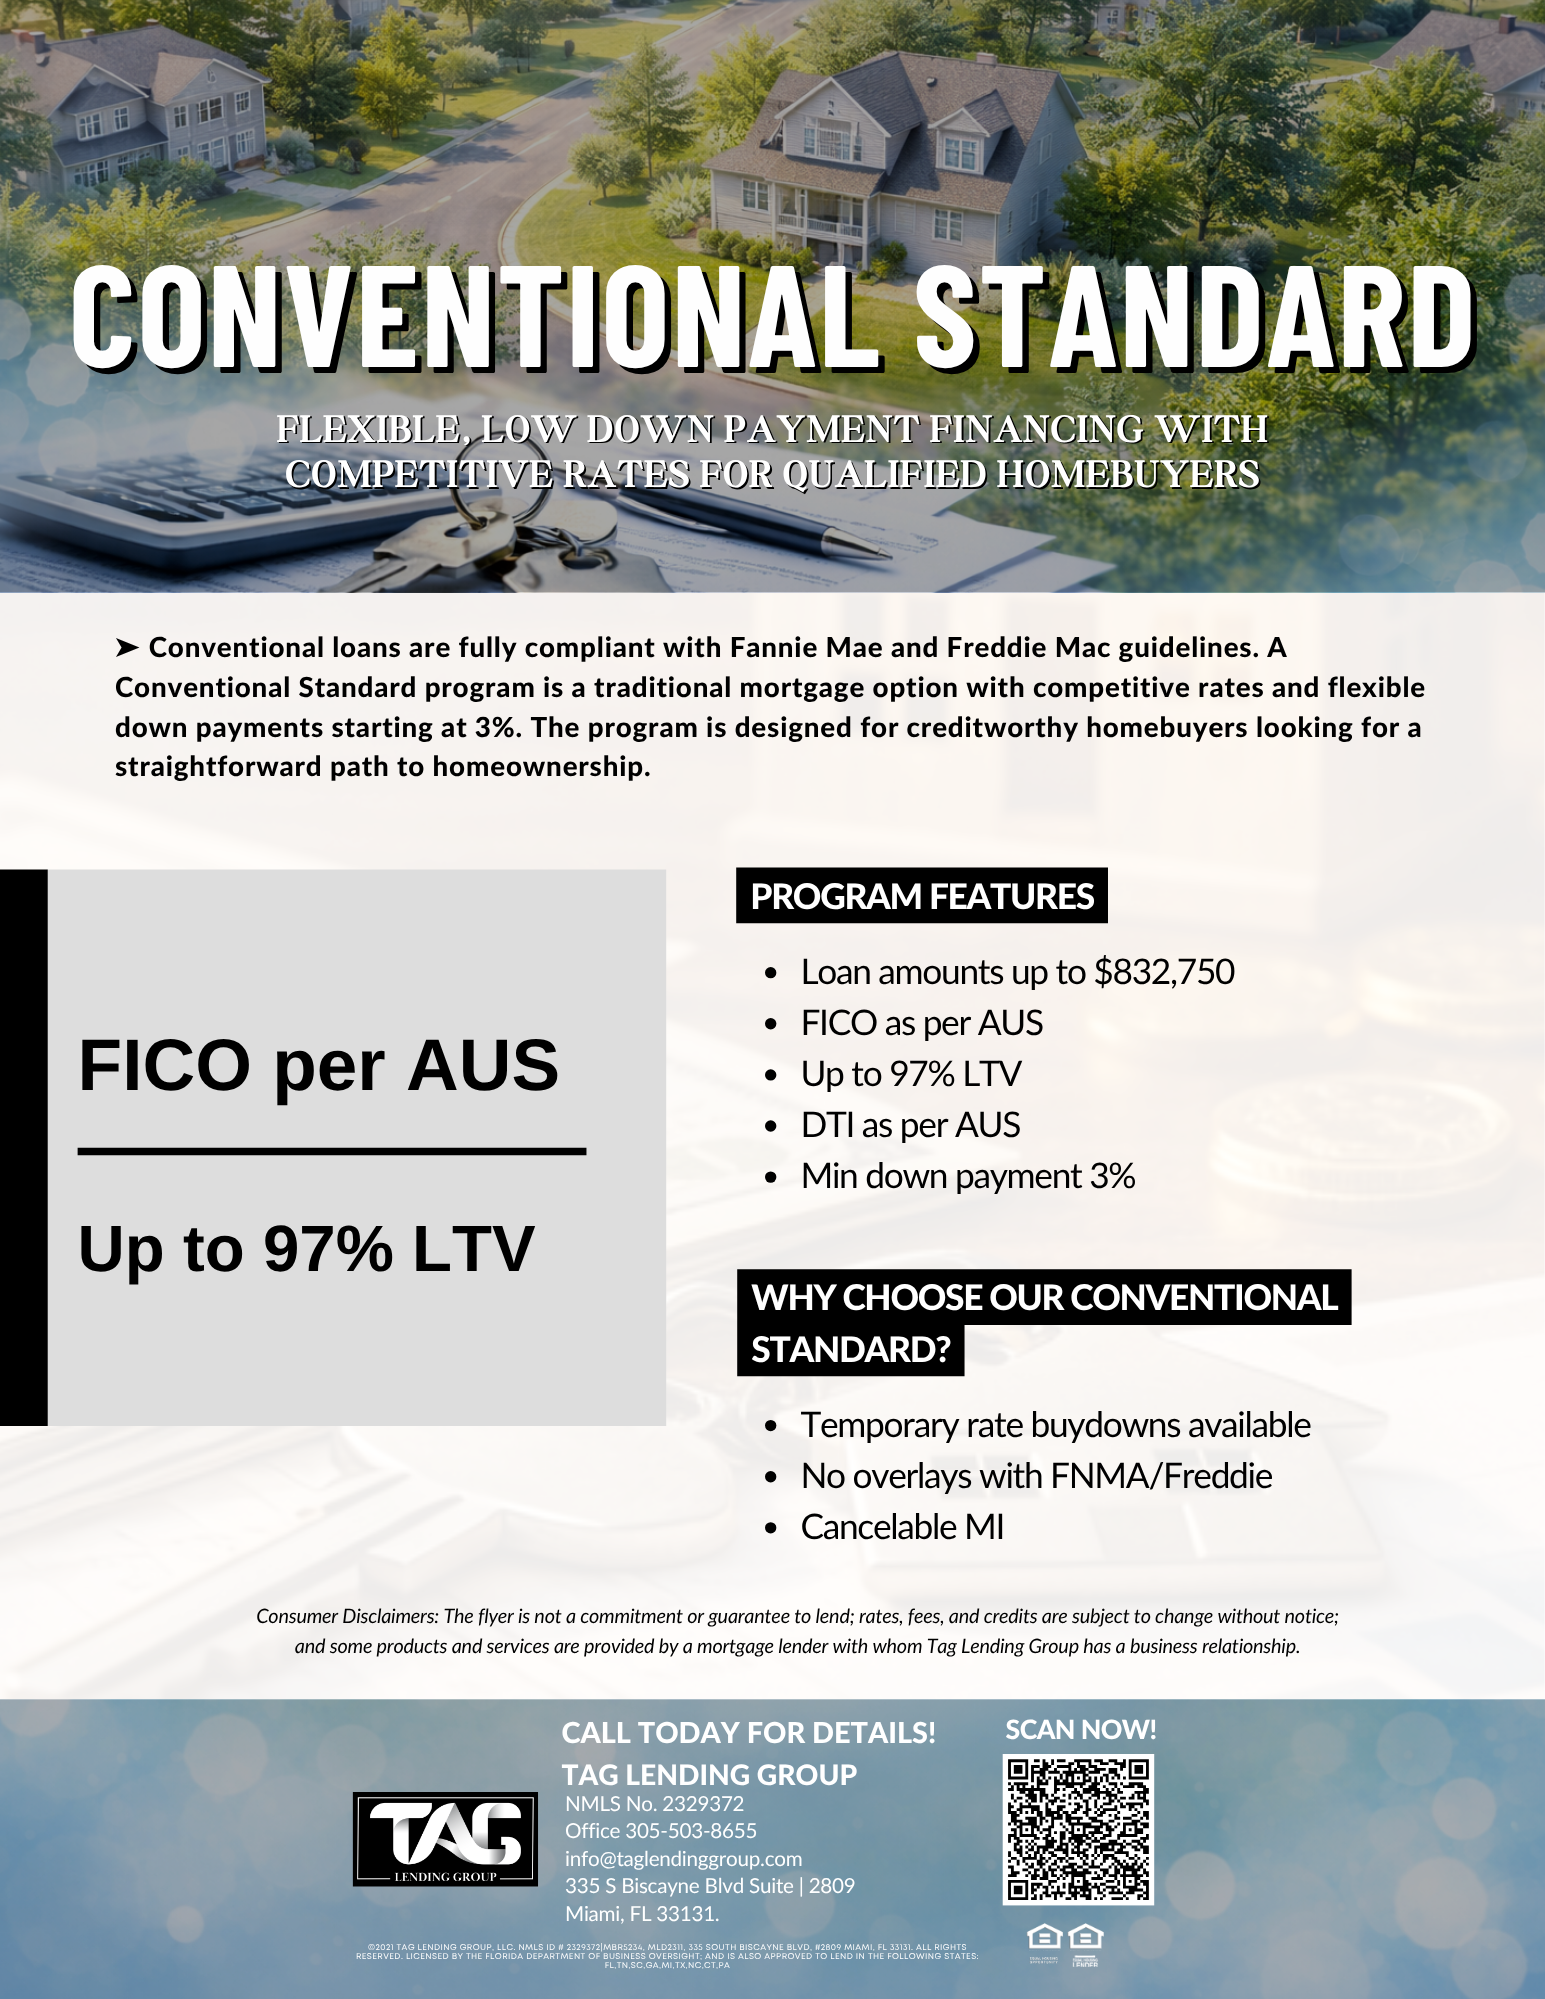
Conventional Standard Program
A traditional mortgage solution for qualified borrowers seeking a reliable path to home financing with standard conventional loan guidelines and flexible options for purchase or refinance needs.
Program Overview
The Conventional Standard Program is designed for qualified borrowers who want a traditional mortgage option for purchasing or refinancing a home. This program can be a strong fit for clients with standard income, credit, and documentation profiles who are looking for a reliable financing path with familiar conventional lending guidelines.
Program Features
Designed for qualified borrowers seeking traditional conventional mortgage financing.
Can be used for eligible home purchase and refinance scenarios.
A strong option for borrowers with stable income, credit, and documentation profiles.
May support primary residence, second home, or investment property scenarios depending on eligibility.
Provides a familiar financing structure for borrowers looking for a standard mortgage solution.
Can be reviewed with a loan officer to determine the best fit based on property type, down payment, credit profile, and borrower goals.
Why Choose This Program?
Offers a trusted mortgage path for borrowers who fit standard conventional guidelines.
Can provide competitive financing for qualified buyers and homeowners.
Supports a clear and familiar qualification process for borrowers with traditional documentation.
Gives realtors a straightforward financing solution for clients with standard borrower profiles.
May be a strong fit for borrowers focused on long-term homeownership, refinance savings, or traditional financing stability.
Allows borrowers to review standard loan options with guidance from an experienced loan officer.
Who This Program Is Great For?
Homebuyers seeking a traditional conventional mortgage option.
Homeowners refinancing an existing mortgage through standard conventional financing.
Borrowers with stable income, solid credit, and standard documentation.
Clients purchasing a primary residence, second home, or eligible investment property.
Borrowers who want a familiar mortgage structure with standard qualification expectations.
Realtors working with qualified buyers who are ready for a traditional financing path.
Download Loan Program
Preview the loan program sheet and download the full Conventional Standard Program details instantly.
Co-Brand Loan Program
Access the co-branded version to share this Conventional Standard Program with your clients and referral partners.
Need Help Structuring a Conventional Loan?
Connect with a loan officer to review your borrower scenario and get clear guidance on the best next step.
Connect To A Loan Officer