USDA LOAN PROGRAM

Affordable government-backed financing for eligible rural and suburban homebuyers

Loan Programs

USDA Loan Program

A government-backed home loan solution designed to help eligible buyers purchase homes in qualified rural and suburban areas with flexible financing options.

Program Overview

The USDA Loan Program is designed to help eligible low-to-moderate income borrowers purchase a primary residence in qualified rural and suburban areas. This program can provide flexible financing with no down payment requirement for qualified buyers who meet USDA property, income, and borrower eligibility guidelines.

Program Features

↗

Designed for eligible properties located in qualified USDA areas.

↗

Allows up to 100% financing for qualified borrowers.

↗

Can help eligible buyers purchase with no down payment requirement.

↗

Available for eligible primary residence purchases.

↗

Subject to USDA income, property, and borrower eligibility guidelines.

↗

A practical solution for buyers seeking affordable government-backed financing.

Why Choose This Program?

↗

A strong option for eligible buyers looking for no-down-payment financing.

↗

Helps make homeownership more accessible in qualified rural and suburban markets.

↗

Can reduce the upfront cash needed to purchase a home.

↗

Provides a government-backed loan option for qualified borrowers.

↗

Supports buyers who meet USDA income and property eligibility requirements.

↗

Gives loan officers another affordable financing solution for eligible clients.

Who This Program Is Great For?

↗

Eligible buyers purchasing a primary residence in a qualified USDA area.

↗

Borrowers looking for a no-down-payment mortgage option.

↗

Clients who meet USDA income and borrower eligibility requirements.

↗

Homebuyers seeking affordable government-backed financing.

↗

Borrowers who want to reduce upfront cash needed to purchase.

↗

Clients who want guidance on USDA property and income eligibility.
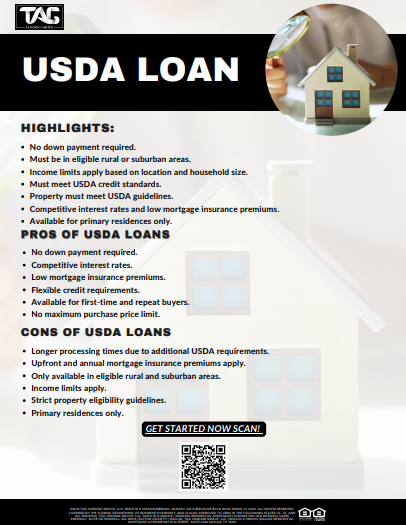
Download Loan Program

Preview the loan program sheet and download the full program details instantly.

Co-Brand Loan Program

Access the co-branded version to share this program with your clients and referral partners.


Need Help Structuring a USDA Loan?

Connect with a loan officer to review your scenario and get clear guidance on eligibility, property location, and the best next step.

Connect To A Loan Officer

USDA Loans at a Glance

Quick answer: A USDA loan is a government-backed mortgage for eligible homes in designated rural and some suburban areas, with 100% financing and no down payment required. Borrowers must meet income and property eligibility rules, and loans are subject to underwriting and USDA guidelines. Last reviewed: November 2026.

100%
Financing, no down payment
620+
Typical min. FICO
Rural
Eligible areas only
USDA
Government-backed

More USDA Loan Details

  • Property must be in a USDA-eligible area; eligibility is checked by address
  • Household income limits apply and vary by area and household size
  • Primary residence only
  • Mortgage insurance in the form of an upfront guarantee fee and annual fee applies
  • Credit, income and property requirements vary by program and lender overlay

USDA Loan FAQs

What is a USDA loan?

A mortgage backed by the U.S. Department of Agriculture to help moderate-income buyers purchase homes in eligible rural and some suburban areas, often with no down payment.

Do I need a down payment for a USDA loan?

No down payment is typically required. USDA loans allow up to 100% financing for eligible borrowers and properties.

How do I know if a property is USDA eligible?

USDA publishes an eligibility map by address. A loan officer can confirm eligibility before you make an offer. Many areas outside major city centers qualify.

Are there income limits for USDA loans?

Yes. Household income must fall within USDA limits for the county and household size. Limits are updated periodically.

What credit score do I need for a USDA loan?

A 620 or higher credit score is typical for streamlined underwriting. Lower scores may be considered with additional review, subject to guidelines.

Can mortgage brokers submit USDA loans to TAG?

Yes. Licensed brokers can submit files through TAG's wholesale channel in the states where TAG is licensed as a lender. No approval or closing date is guaranteed.

×

⭐ Our Google Reviews

Geraldine ⭐⭐⭐⭐⭐ I had the absolute pleasure of working with Tag Lending Group and can't say enough about the incredible experience...
Jaelyn ⭐⭐⭐⭐⭐ Vera was extremely helpful during our home buying process. The whole team made it so smooth and stress-free...
Logan ⭐⭐⭐⭐⭐ Anthony was fantastic and informative. They made my tricky situation look easy and worked hand in hand with me...
Some additional information in one line