SmartBuy DPA Program
Down payment assistance for FHA borrowers with three ways to structure it: two forgivable options and one repayable option, with no income limits, so the assistance can match each borrower’s plans.
Program Overview
SmartBuy is down payment assistance for borrowers using an FHA first mortgage. Instead of a one-size-fits-all program, it offers three options that differ in how much assistance is provided, whether it must be repaid, and what the funds can cover.
Assistance is provided as a grant or as a second mortgage (second lien) recorded behind the FHA first mortgage. Depending on the option, funds can be used for the down payment alone or for the down payment plus closing costs, fees, and prepaid items. Options 2 and 3 are also available on rate-and-term refinances.
Compare the Three SmartBuy Options
| Option 1 (Forgivable) | Option 2 (Forgivable) | Option 3 (Repayable) | |
|---|---|---|---|
| Assistance | 5% grant or second lien | 3.5% or 5% of the sales price | Up to 5% of the sales price |
| Term | Follows the FHA 30-year fixed first mortgage | 5 years; 100% forgiven after 5 years | 10-, 20-, or 30-year terms |
| Interest or payment on the 2nd | None | None | Yes, interest and a monthly payment apply |
| Use of funds | Down payment | Down payment, closing costs, fees, prepaids | Down payment, closing costs, fees, prepaids |
| Transactions | Purchase only | Purchase and rate-and-term refinance | Purchase and rate-and-term refinance |
| Eligible property | Primary residence only | Primary residence: single-family, condo, PUD, 2-unit, manufactured (doublewide OK) | Primary residence: single-family, condo, PUD, manufactured (doublewide OK) |
| Minimum FICO | 600 | 620 (manufactured homes 640) | 660 |
| Blended credit | Not available | 660 on borrower, no minimum on co-borrower | 670 on borrower, no minimum on co-borrower |
| Underwriting | AUS approval required; not available when the first mortgage is FHA High Balance | AUS; manual underwriting by exception only (640 min FICO) | AUS only; manual underwriting not allowed |
All options: no income limits, gift funds allowed, and seller concessions per FHA guidelines. Guidelines are subject to change; confirm current terms with your loan officer.
Program Features
Three assistance structures to fit different borrower plans.
No income limits on any option.
Gift funds allowed on all options.
Options 2 and 3 can cover closing costs, fees, and prepaids, not just the down payment.
Options 2 and 3 are available on rate-and-term refinances.
Eligible properties include single-family homes, condos, PUDs, manufactured homes, and 2-unit homes (Option 2).
Why Choose This Program?
Option 2 carries no interest and no monthly payment, and is 100% forgiven after 60 payments on the first mortgage when program terms are met.
Option 3 offers repayment flexibility with 10-, 20-, or 30-year terms.
Credit options starting at a 600 minimum FICO (Option 1).
Blended-credit paths allow a co-borrower with limited credit history (Options 2 and 3).
Seller concessions allowed per FHA guidelines.
Helps buyers preserve savings for reserves, moving costs, and post-closing needs.
Forgiveness Terms
Per the SmartBuy program sheet, the following terms apply to the forgivable down payment assistance second mortgage:
After 60 payments, if the first mortgage is current at the time of payoff, the down payment assistance second is forgiven.
If the first mortgage is paid off before 60 payments are made, for example through a sale or refinance, the full amount of the down payment assistance second becomes due and payable.
The property must remain owner-occupied through the 60th payment, or the down payment assistance second will be called due and payable.
The down payment assistance second cannot be resubordinated, so it must be paid off if the first mortgage is refinanced.
Who This Program Is Great For
Buyers whose income is above the limits of many state and local DPA programs.
Borrowers who need help with closing costs as well as the down payment.
Buyers who plan to stay in the home at least five years (Option 2).
Borrowers with credit scores starting at 600 (Option 1).
Owners of a primary residence considering a rate-and-term refinance with assistance (Options 2 and 3).
Real estate and broker partners who want to match the DPA structure to each client.
SmartBuy DPA FAQs
What is the difference between forgivable and repayable down payment assistance?
Forgivable assistance does not need to be repaid if you meet the program terms, such as keeping the home as your primary residence and keeping the first mortgage in place for a set period. Repayable assistance is a second mortgage with its own interest rate and monthly payment that is paid back over its term.
Is there an income limit for SmartBuy?
No. Unlike many state and local down payment assistance programs, SmartBuy has no income limits on any of its three options.
What credit score do I need?
It depends on the option: 600 for Option 1, 620 for Option 2 (640 for manufactured homes), and 660 for Option 3. Blended-credit options are available on Options 2 and 3.
What happens if I sell or refinance within five years?
For the forgivable second, if the first mortgage is paid off before 60 payments are made, the full amount of the assistance becomes due and payable at that time.
Can I use gift funds with SmartBuy?
Yes. Gift funds are allowed on all three options, subject to FHA documentation requirements.
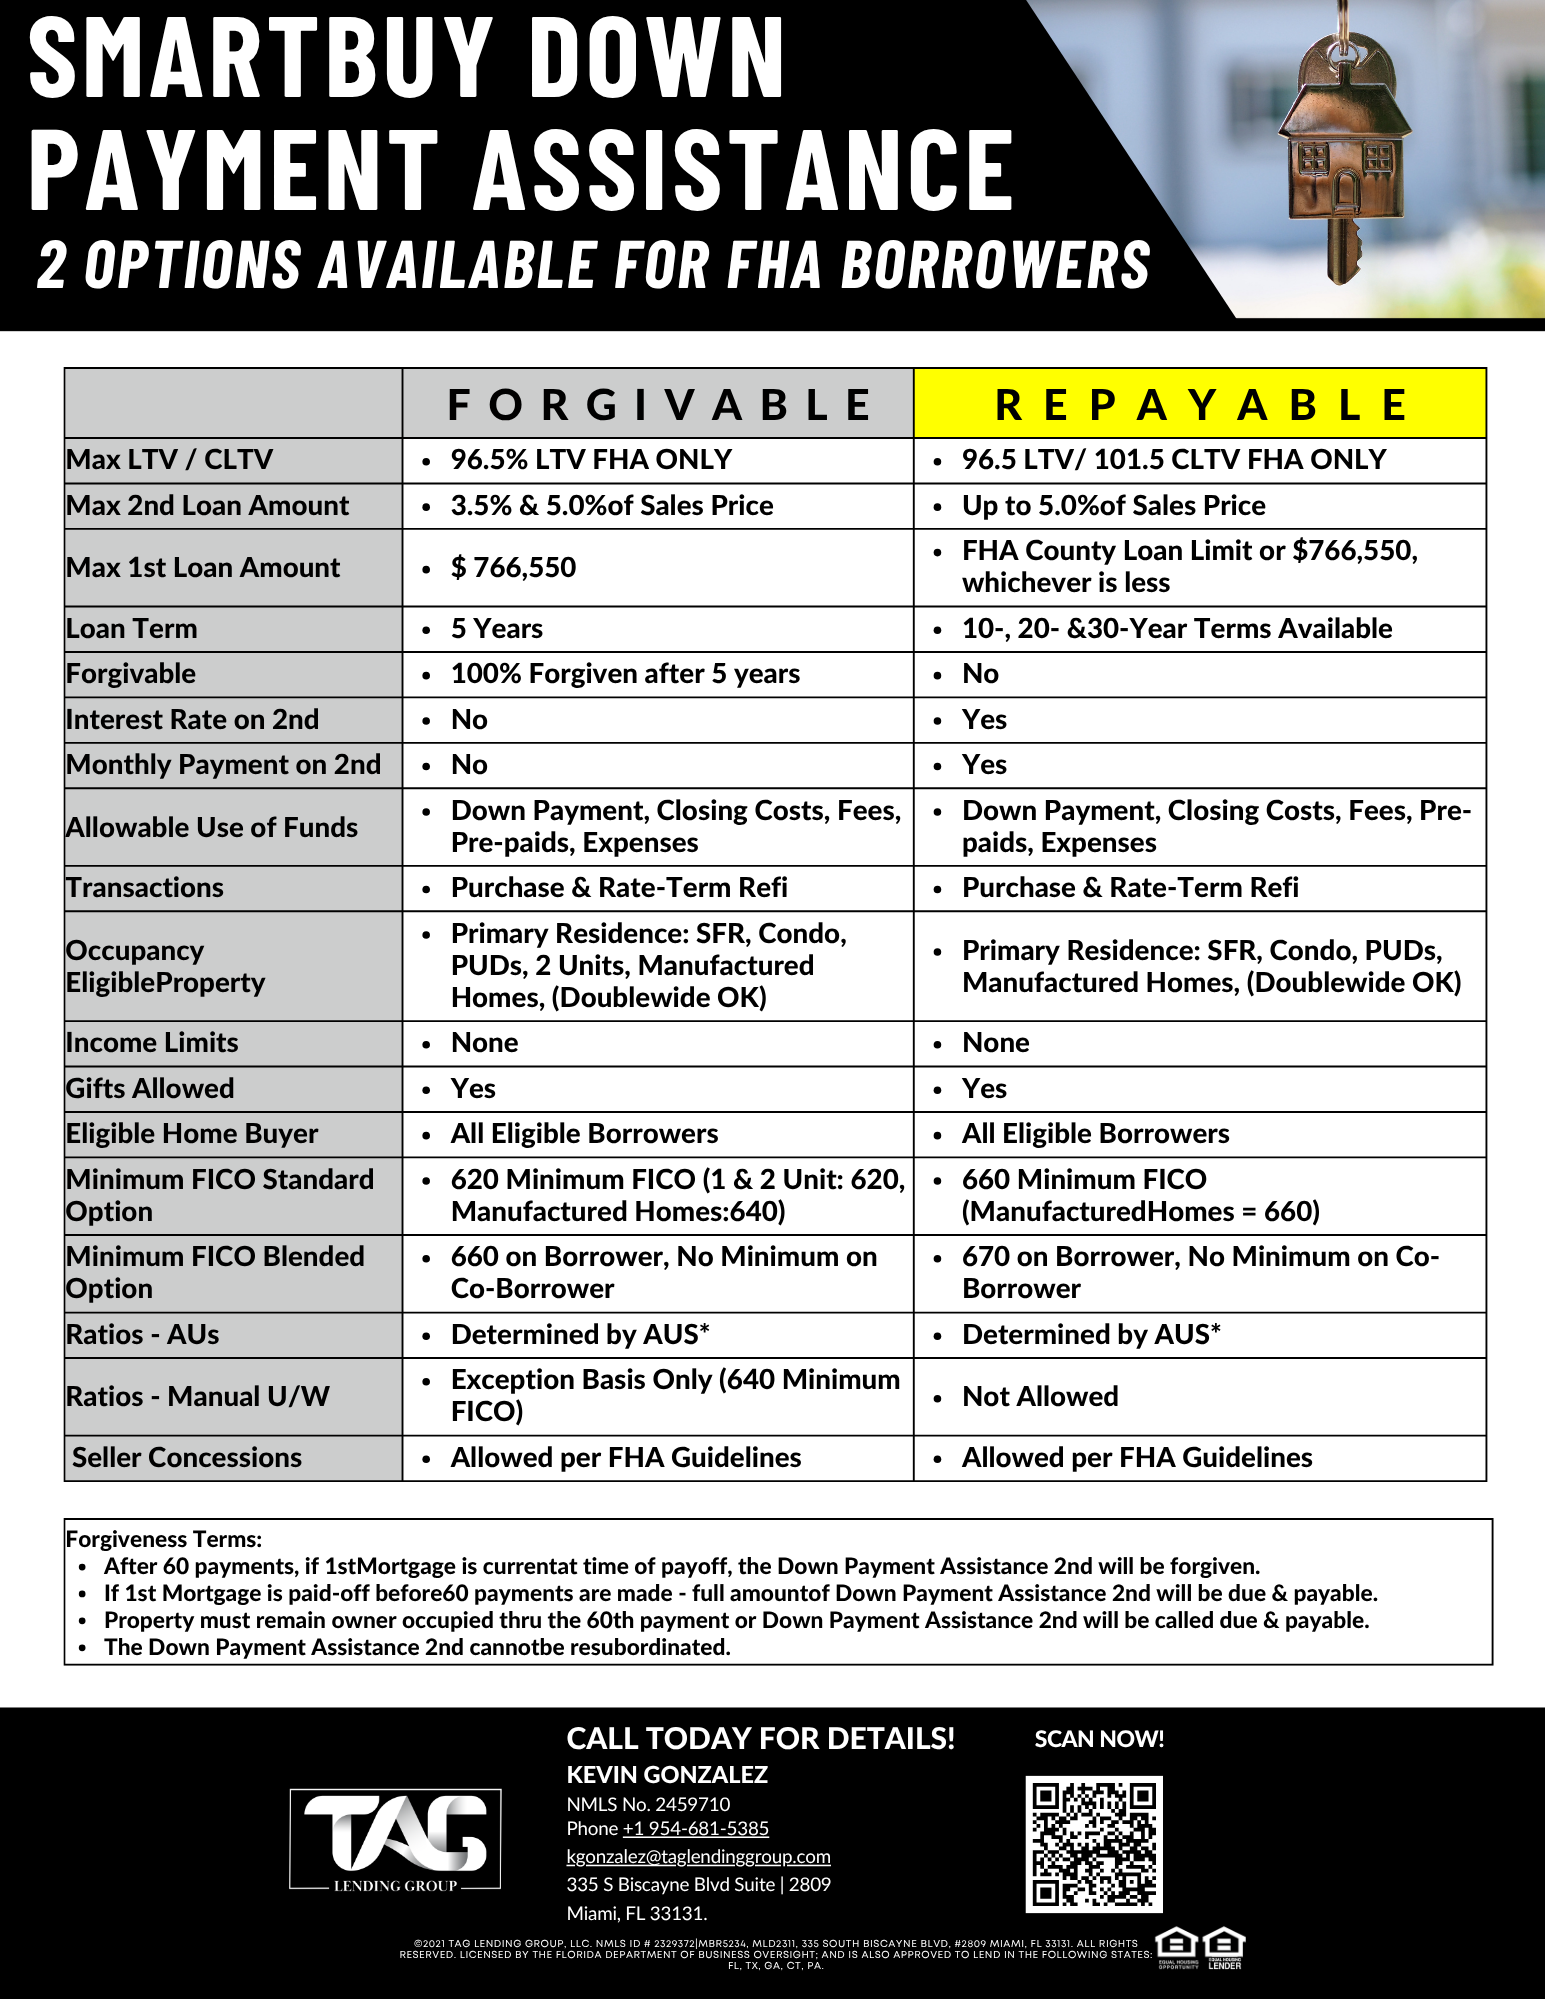
Download Loan Program
Preview the SmartBuy DPA program sheet with the full option-by-option guidelines.
Co-Brand Loan Program
Access the co-branded version to share this program with your clients and partners.
Need Help Choosing a SmartBuy Option?
Connect with a loan officer to compare options for your scenario and get clear guidance on the best next step.
Connect To A Loan Officer