HomeStart DPA Program
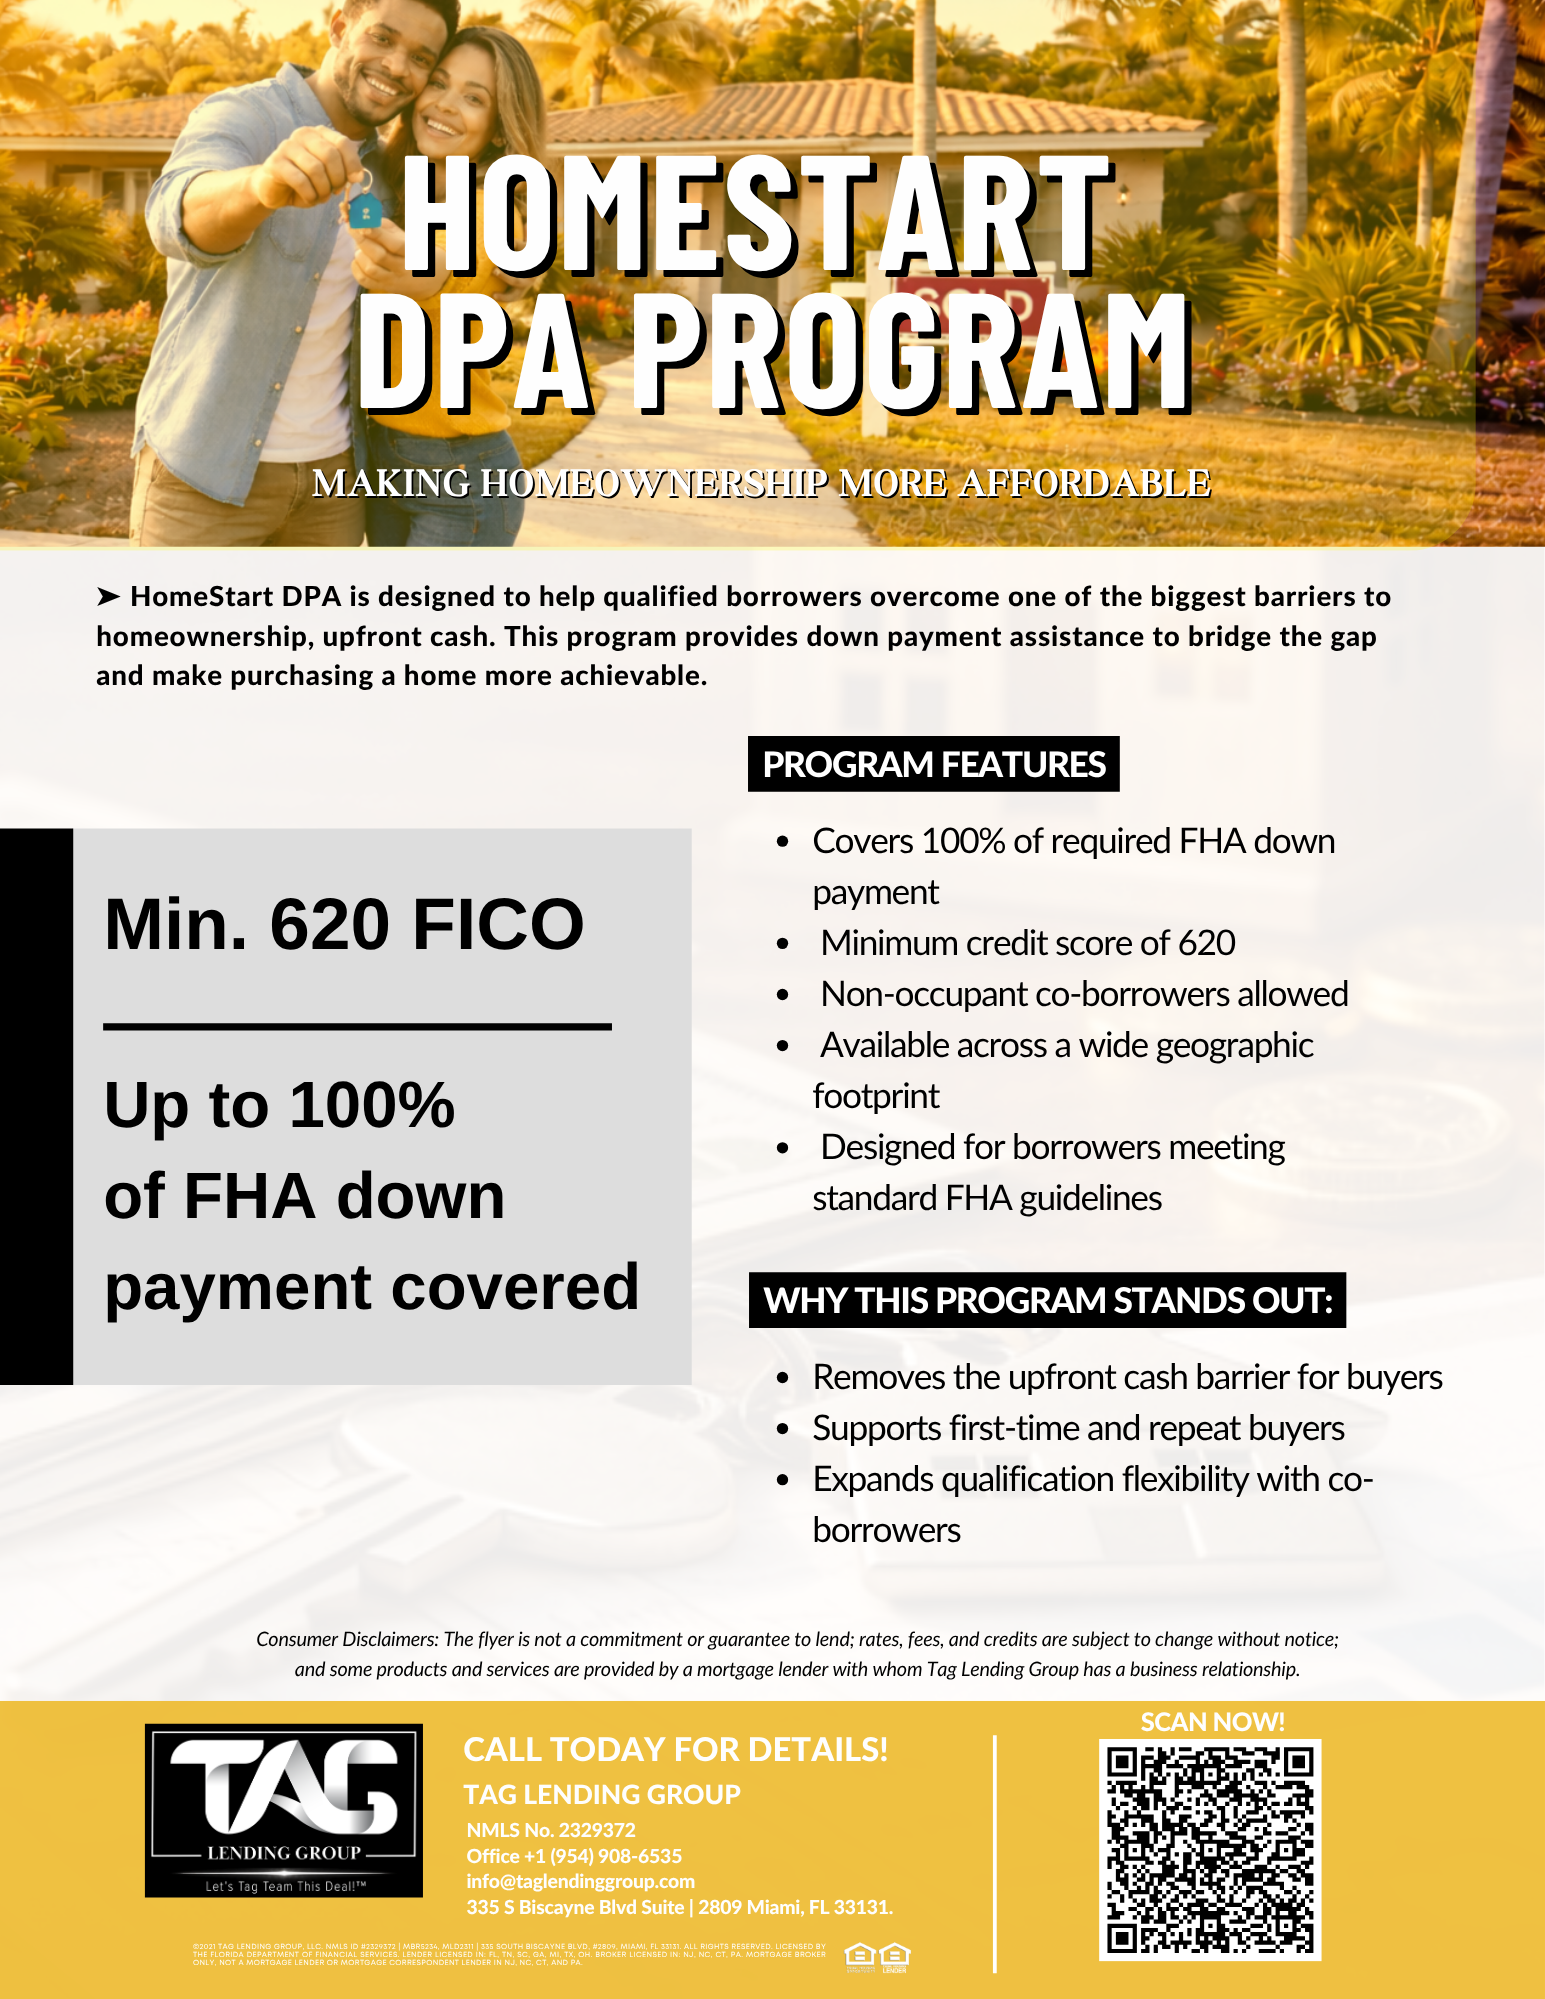
FHA down payment assistance that can cover up to 100% of the minimum required down payment, helping eligible first-time and repeat buyers overcome the biggest barrier to homeownership: upfront cash.
Program Overview
HomeStart DPA is a down payment assistance program paired with an FHA first mortgage. It is designed to help qualified borrowers overcome one of the biggest barriers to buying a home, the upfront cash, by covering up to 100% of the required FHA down payment.
FHA loans are insured by the Federal Housing Administration and require a minimum down payment of 3.5% of the purchase price for borrowers with a credit score of 580 or higher. On a $300,000 home, that is $10,500 due at closing. HomeStart can provide assistance toward that required amount for borrowers who meet the program’s 620 minimum credit score and standard FHA guidelines.
Program Features
Covers up to 100% of the minimum required FHA down payment.
620 minimum credit score.
Non-occupant co-borrowers allowed, such as a parent or relative who will not live in the home.
Paired with an FHA first mortgage and underwritten to standard FHA guidelines.
For the purchase of a primary residence, as required for FHA financing.
Available across a wide footprint in states where Tag Lending Group is licensed, subject to program availability.
Why Choose This Program?
Removes the down payment barrier, often the largest upfront cost of buying a home.
Open to both first-time and repeat buyers.
Co-borrower flexibility can help borrowers qualify on income.
Lets buyers keep savings for closing costs, reserves, moving expenses, or repairs.
Built on FHA financing, known for flexible credit and debt-to-income standards.
Can help eligible buyers purchase sooner instead of saving for years.
How HomeStart Works with an FHA Loan
Review your scenario. A TAG loan officer reviews credit, income, and property details to confirm FHA and HomeStart eligibility.
Apply for the FHA first mortgage and HomeStart together. Both are underwritten as part of the same purchase transaction.
Assistance is applied at closing. HomeStart funds go toward the required FHA down payment.
Plan for remaining costs. Closing costs, prepaid items, escrows, and FHA mortgage insurance premiums still apply. Seller concessions or gift funds may help where FHA guidelines allow.
Who This Program Is Great For
First-time buyers with steady income who have not saved a full down payment.
Repeat buyers who want to preserve cash when moving or relocating.
Borrowers with credit scores of 620 or higher who meet FHA guidelines.
Households qualifying with help from a non-occupant co-borrower.
Buyers who prefer to keep savings in reserve for repairs or emergencies.
Real estate and broker partners looking for a simple, single-structure FHA DPA option.
HomeStart DPA FAQs
What is the minimum down payment on an FHA loan?
FHA requires at least 3.5% down for borrowers with a credit score of 580 or higher, and 10% for scores between 500 and 579. Because HomeStart requires a 620 minimum score, the 3.5% minimum applies, and HomeStart can cover up to 100% of it.
Is HomeStart only for first-time homebuyers?
No. HomeStart supports both first-time and repeat buyers who meet program and FHA guidelines and will occupy the home as their primary residence.
What is a non-occupant co-borrower?
A co-borrower who signs the loan, and whose income may count toward qualifying, but who will not live in the home, such as a parent or other family member. Co-borrowers must meet FHA and program requirements.
Does HomeStart cover closing costs?
HomeStart is designed to cover the required down payment. Closing costs, prepaid items, and escrows still apply and may be covered by seller concessions, lender credits, or gift funds where FHA guidelines allow. Your Loan Estimate will show the cash needed to close.
Do I have to repay the assistance?
Repayment or forgiveness terms depend on how the assistance is structured for your loan. Your loan officer will explain all terms before you commit, and they will appear in your loan disclosures.
Download Loan Program
Preview the HomeStart DPA program sheet and download the full program details.
Co-Brand Loan Program
Access the co-branded version to share this program with your clients and partners.
Need Help Structuring a HomeStart DPA Loan?
Connect with a loan officer to review your scenario and get clear guidance on the best next step.
Connect To A Loan Officer